

Blogs
Logistics Robots Market 2032: Why 16.8% CAGR and 63% Palletizing Shift Redefine Growth
By PW Consulting, 2026-09-21
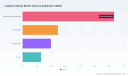
The Logistics Robots Market: Navigating Growth, Innovation, and Strategic Opportunity
The logistics robots market has evolved from a niche automation segment into a foundational pillar of modern supply chain infrastructure. Between 2020 and 2025, the market expanded from approximately $66.8 million to $120.5 million, reflecting a compound annual growth rate of 16.8% that extends through the 2026–2032 forecast window. By the end of the projection period, revenue is expected to approach $295 million, driven by sustained adoption across warehousing, material handling, and last-mile operations. This trajectory is not merely a function of technological novelty; it represents a structural realignment in how goods are moved, sorted, and stored amid persistent labor constraints, rising throughput expectations, and the need for operational resilience.
Within this growth story, concentration patterns reveal a market still in transition. The top three players capture roughly 45% of revenue, while the top five account for 56%, indicating a landscape where established automation vendors coexist with agile, software-driven entrants. The diversity of offerings—from automated guided vehicles and autonomous mobile robots to robotic arms and specialized end-effectors—demonstrates that logistics automation is no longer a one-size-fits-all proposition. Instead, success increasingly depends on how well solutions integrate with existing facility layouts, warehouse management systems, and broader enterprise data architectures.
Market Landscape and Critical Inflection Points
From Isolated Automation to Ecosystem Integration
For much of the past decade, logistics robotics deployments focused on discrete, repeatable tasks within controlled environments. Today, the prevailing shift is toward layered automation ecosystems where mobile platforms, fixed automation, and software orchestration converge. Facilities are no longer evaluating robots as standalone tools; they are assessing how robotic fleets interact with inventory algorithms, demand forecasting models, and labor scheduling systems. This integration imperative is reshaping procurement cycles, implementation timelines, and the value proposition of vendors who can deliver both hardware reliability and intelligent software layers.
Labor Dynamics and Throughput Pressure
Persistent workforce volatility continues to act as a fundamental catalyst. High turnover, shifting labor availability, and escalating training costs have pushed operators to seek automation that augments rather than entirely replaces human activity. At the same time, consumer expectations for faster, more accurate fulfillment have compressed tolerance for bottlenecks. The result is a market where throughput per square foot, error reduction, and flexibility during demand spikes have become central decision criteria. Companies are increasingly treating robotics not as a capital expenditure isolated from operations, but as a lever for stabilizing service levels under variable conditions.
Worldwide Logistics Automatic Robotics Machine Market
Cost Structures and Implementation Complexity
While the promise of automation is clear, the economics of deployment remain uneven. Upfront capital, integration effort, and change management requirements can delay payback periods, particularly for mid-sized operators. Steel tariffs of 25% implemented in 2025 have added pressure to equipment costs across robotics and conveyor systems, with domestic steel price increases partially neutralizing the expected advantages of localized sourcing. These dynamics are pushing buyers to evaluate total cost of ownership more rigorously, favoring solutions that minimize retrofit complexity, support phased rollouts, and offer predictable operating expenses.
Core Drivers Shaping Market Trajectory
Technological Innovation and Embodied Intelligence
The most consequential driver is the maturation of embodied intelligence and AI-enabled navigation. Modern autonomous mobile robots are increasingly capable of dynamic path planning, obstacle recognition, and task adaptation without extensive fixed infrastructure. Recent product introductions illustrate this direction: in May 2026, SEER Robotics launched an AI delivery robot ready for immediate deployment alongside an embodied wheeled humanoid robot base, signaling a push toward versatile platforms that can handle both final-mile delivery and warehouse operations. Similarly, Geek+ introduced its Brain embodied intelligence platform and RoboShuttle V5 at MODEX 2026, reinforcing the industry’s move toward software-defined robotics that can be reconfigured as operational needs change.
These advancements reduce the traditional friction of warehouse automation: fixed guide paths, extensive site preparation, and rigid workflow assumptions. Instead, fleets can be scaled incrementally, retasked across shifts, and coordinated through centralized orchestration layers. For operators, this means automation can follow demand rather than requiring demand to conform to automation design. For vendors, differentiation is shifting from mechanical performance alone to the quality of perception, fleet coordination, and integration APIs.
Policy, Safety Standards, and Regulatory Clarity
Regulatory and standards development is quietly reshaping deployment confidence. The ANSI/A3 R15.06-2025 safety standard, which updates ISO 10218-1:2025, introduces revised risk assessment practices, functional safety expectations, and cybersecurity requirements for industrial robots. As safety frameworks become more explicit, organizations gain clearer guidance for integrating collaborative and autonomous systems alongside workers, reducing ambiguity that historically slowed adoption in mixed human-robot environments.
Policy momentum is also emerging in specific geographies. In the United Kingdom, the 2025 Industrial Strategy and Digital and Technologies Sector Plan introduced reforms including a Regulatory Innovation Office and a clearer route to market for delivery robots. Such developments matter because they reduce time-to-deployment uncertainty for last-mile and urban logistics applications. When regulators provide predictable pathways, innovators can invest with greater confidence, and operators can plan pilots with more reliable approval timelines.
Demand-Side Shifts and the Rise of Robotics-as-a-Service
On the demand side, adoption patterns are broadening beyond large-scale distribution centers. As of November 2025, 60% of U.S. warehouses had integrated AI into their operations, with projections indicating this figure could reach 80% in the coming years. This AI penetration is closely intertwined with robotics adoption because intelligent software layers make robotic fleets more useful: they enable better task allocation, predictive maintenance, and dynamic responsiveness to order profiles.
The economics of adoption are also evolving through Robotics-as-a-Service models, which grew by 42% according to IFR World Robotics 2025 data. IFR reported 102,900 transportation and logistics robots sold in 2024, making this the largest professional service robot application class. RaaS growth reflects a preference among many operators for variable-cost models that lower upfront capital exposure and align automation expenses with utilization. For a market where operational flexibility is paramount, subscription and outcome-based pricing are becoming meaningful differentiators, particularly for seasonal businesses and companies managing multiple sites with varied automation needs.
Supply Chain Realities and Cost Resilience
Supply chain volatility continues to influence purchasing behavior and vendor selection. Beyond steel tariffs, organizations are weighing the resilience of their automation supply chains: component availability, lead times, and service support networks all affect the reliability of robotic deployments. Vendors that provide transparent supply chain strategies, modular hardware designs, and robust remote support capabilities are gaining favor because they reduce the risk of prolonged downtime. In parallel, the push toward software-defined fleets is making it easier to adapt hardware bases to new tasks via firmware and orchestration updates, which helps protect prior investments as operational requirements change.
Competitive Dynamics and Strategic Positioning
Portfolio Breadth Versus Specialized Excellence
The competitive field spans global automation incumbents, AMR specialists, and emerging players focused on embodied intelligence, humanoid platforms, and cloud robotics. Companies such as Amazon Robotics, ABB, KUKA, Toyota Industries, Fanuc, Yaskawa, KION Group, Daifuku, and MiR bring scale, industrial manufacturing heritage, and deep integration experience. Their competitive strength often lies in the ability to combine robotics with broader material handling systems, service networks, and long-standing customer relationships.
At the same time, specialist firms are carving distinct positions. Geek+ has maintained a leading position in AMR and embodied intelligence warehouse logistics, emphasizing full fleet solutions for order fulfillment and storage. Locus Robotics focuses on AI-powered autonomous mobile robots and robots-to-goods picking systems that align closely with labor-constrained picking workflows. Rapyuta Robotics promotes cloud robotics with ASRS and upgraded PA-AMR systems designed for modular warehouse automation, appealing to operators seeking flexibility across site configurations. Addverb Technologies has expanded its footprint with carousel automation and interface robots tailored for high-order storage centers, while Exotec has pushed higher-density storage through next-generation Skypod systems with advanced software and improved space utilization.
Differentiation Through Software, Safety, and Service
Hardware motion is increasingly table stakes; competitive advantage is accruing to firms that excel in fleet orchestration, safety certification, and service economics. The emphasis on updated safety standards and cybersecurity requirements elevates the importance of vendors who can document compliance rigorously and support secure integration with enterprise IT. Service models are equally critical: remote diagnostics, over-the-air updates, and predictable maintenance windows reduce the operational burden on warehouse teams and strengthen the business case for automation. In markets where labor is scarce and skilled technicians are even scarcer, service reliability can be as decisive as robot speed or payload.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market is unlikely to settle into a single dominant structure. Instead, it is evolving along multiple axes. Large automation groups may consolidate capabilities through acquisitions that add software, vision, or mobile capabilities to fixed automation portfolios. Simultaneously, fragmentation persists at the application layer, where niche players address specific workflows such as tote handling, final-mile delivery, or high-density storage. New entrants are also emerging with humanoid and embodied platforms, expanding the design space beyond traditional pallet and cart movement. This pluralistic structure benefits buyers because it creates options across price points, deployment styles, and integration complexity, but it also complicates vendor selection and underscores the need for clear evaluation criteria aligned with operational goals.
Forward Outlook: Three Trends Defining the Next Wave
Trend 1: Software-Defined Fleets Become the Norm
Over the next three to five years, the market will increasingly separate the value of hardware from the value of orchestration. Robots will be expected to adapt to changing layouts, task mixes, and throughput targets through software upgrades rather than physical reconfiguration. This trend favors platforms with open integration architectures, robust simulation tools, and analytics that help operators optimize task assignment and utilization. The commercial opportunity lies in solutions that can demonstrate measurable improvements in pick density, travel efficiency, and changeover time without requiring major facility redesign.
Trend 2: Broader Application Footprints Beyond Traditional Warehousing
While palletizing, de-palletizing, pick-and-place, and internal transportation remain dominant use cases, the application frontier is expanding. Final-mile deliveries, mixed human-robot collaboration in active aisles, and modular automation for smaller sites are gaining traction. In the United Kingdom, regulatory reforms have opened clearer routes for delivery robots, and product launches in embodied wheeled platforms point toward more versatile machines capable of operating across warehouse and urban environments. As these applications mature, the market will likely see more cross-site deployments where the same platform family supports multiple functions, improving asset utilization and simplifying fleet management.
Trend 3: Cost Optimization and Phased Adoption Models
Given equipment cost pressures and integration complexity, adoption will continue to shift toward phased rollouts and flexible financial models. Operators will favor deployments that prove value in a limited area before expanding, especially when steel tariffs and domestic material costs elevate baseline equipment expenses. Robotics-as-a-Service and outcome-linked pricing will remain attractive for organizations seeking to manage capital exposure and align automation spend with volume variability. Vendors that can offer transparent cost structures, scalable pilots, and rapid time-to-value will be better positioned to convert interest into committed deployments.
PW Consulting Automotive & Machinery Research Center
Risks and Uncertainties to Monitor
Several factors could temper or redirect growth. 만일 steel and component cost pressures persist, payback periods may lengthen for capital-intensive projects, slowing adoption among price-sensitive segments. Regulatory divergence across regions could create uneven deployment paths, particularly for mobile and delivery applications that cross jurisdictional boundaries. Cybersecurity expectations will continue to rise, requiring vendors and operators to invest in secure integration and data governance. Finally, the pace of AI adoption in warehouses will influence how quickly robotic fleets realize their full potential; without strong software integration and change management, advanced hardware can underperform relative to expectations.
Strategic Actions for Decision-Makers
For Manufacturers and Automation Vendors
Differentiate beyond kinematics. The most defensible positions will combine reliable mobile platforms with strong orchestration software, clear safety and cybersecurity documentation, and service models that reduce operational friction. Prioritize integration readiness with existing warehouse management and enterprise systems, and invest in simulation and deployment tooling that shortens implementation cycles. As application diversity increases, modular hardware and flexible tasking capabilities will help customers adapt without discarding prior investments.
For Investors
Look for value creation at the intersection of software, fleet management, and service economics. Companies that can demonstrate repeatable deployment processes, strong utilization metrics, and scalable RaaS or outcome-based models are better aligned with the market’s shift toward flexible cost structures. Pay attention to safety compliance maturity and cybersecurity posture, as these increasingly influence procurement decisions in mixed-use environments. Sector breadth matters too: exposure across warehousing, material handling, and final-mile applications can provide resilience if one segment slows.
For Procurement and Operations Leaders
Define the problem before selecting the platform. Clarify whether the priority is throughput stability, labor augmentation, space efficiency, or flexibility across sites, then evaluate vendors against those outcomes rather than nominal specifications. Favor phased pilots that can validate performance under real order profiles, and model total cost of ownership with realistic integration and service costs. As equipment cost pressures persist, consider flexible financial models and modular deployments that let you scale credible results rather than committing to large fixed installations upfront.
From Insight to Execution
The logistics robots market is moving from rapid expansion to more nuanced value creation. Growth rates remain strong, but the next phase will reward those who can align automation with operational realities: integration complexity, safety expectations, cost pressures, and the need for flexible deployment models. Companies that treat robotics as part of a broader, software-enabled logistics strategy will be better equipped to capture the upside while managing risk.
For decision-makers seeking detailed segmentation data, regional and application-level revenue breakdowns, competitor benchmarking, and customized strategic recommendations, the full PW Consulting research report provides the granular evidence base needed to translate these market dynamics into concrete investment and deployment decisions.
Worldwide Warehouse Robots Market
For detailed analysis of this topic, please visit the official page: Logistics Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ear Wash Station Market: Beyond the 4.65% CAGR Story—Key Shifts Explained
By PW Consulting, 2026-09-21
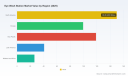
The Eye Wash Station Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for emergency eye wash stations has entered a phase of measured, steady expansion. From 2020 through 2025, total market revenue climbed from approximately USD 300.0 million to USD 435.0 million, reflecting a compound trajectory that underscores the essential nature of workplace safety infrastructure. Looking ahead to the 2026–2032 forecast horizon, the market is projected to grow at a CAGR of 4.65 percent, reaching an estimated USD 596.0 million by 2032. This growth profile is not explosive, but it is structurally resilient. Emergency first-aid equipment sits at the intersection of regulatory compliance, industrial activity levels, and organizational risk management priorities. As long as those foundational drivers remain intact, the market maintains a predictable revenue floor alongside pockets of incremental upside.
Behind the headline numbers, however, lie structural shifts that demand attention from manufacturers, distributors, procurement leaders, and investors. The market is no longer moving purely on compliance-driven replacement cycles. It is being reshaped by evolving technical expectations, tightening performance standards, supply chain recalibration, and shifting application profiles across high-exposure industries. Understanding these dynamics is essential for anyone positioning themselves in the safety equipment space.
Current Market Landscape and Critical Challenges
The eye wash station market operates as a mature but still evolving segment within the broader workplace safety equipment ecosystem. Revenue growth over the past half-decade has been supported by steady industrial output, ongoing laboratory expansion, and consistent investment in occupational health infrastructure. Rather than experiencing abrupt cyclical swings, the market reflects the incremental nature of compliance upgrades, facility build-outs, and periodic modernization programs. The forecast period through 2032 suggests continued expansion, but at a pace that rewards companies with disciplined product planning, strong service networks, and clear differentiation rather than those relying solely on volume-driven commoditization.
Three core challenges and inflection points are shaping how participants navigate the market today.
Compliance complexity and specification drift. Emergency eyewash requirements are not static checklists. Regulatory frameworks and recognized standards continue to refine expectations around water temperature, flow consistency, activation speed, and maintenance protocols. For manufacturers and specifiers alike, this creates a moving target: products must satisfy baseline compliance while also aligning with installation practices, testing routines, and user training expectations that vary by facility type, region, and internal safety policies. The challenge is not simply meeting a standard once; it is designing systems that remain compliant over their service life under real operating conditions.
Total cost of ownership versus upfront purchase price. Many procurement decisions still default to initial cost, even though the operational footprint of an eyewash station can be substantial. Plumbed systems involve plumbing integration, water quality management, and ongoing testing programs. Self-contained units reduce infrastructure dependence but require cartridge or solution replacement, inventory management, and scheduled service. Combination units and higher-performance configurations add complexity and cost. Organizations increasingly need to evaluate installed cost, maintenance burden, downtime risk, and compliance documentation rather than treating eyewash stations as discrete commodity purchases.
Uneven adoption across facility types and geographies. While large industrial operators and accredited laboratories tend to have mature safety programs, smaller facilities, newer industrial zones, and certain emerging market environments may lag in standardization. This creates a bifurcated market where some segments demand advanced features and frequent replacement cycles, while others remain price-sensitive or delay investment until regulatory inspection or incident-driven reassessment forces action. Participants must therefore balance portfolio scope: offering accessible entry-level solutions while preserving higher-margin options for performance-conscious buyers.
These challenges also represent the market's pressure points for innovation. Companies that reduce compliance uncertainty, simplify maintenance, or make total cost easier to quantify are better positioned to capture specification wins and retain end users over time.
Key Drivers Shaping the Market
The market's trajectory is being pulled by several interconnected forces. Individually, each matters; together, they define where growth is likely to concentrate and where competitive advantage will be earned.
Eye Anatomical Model Market
Technical innovation and performance differentiation
One of the most significant drivers is the ongoing push toward better flushing performance, faster activation, and more predictable user experience. Innovative rinsing technologies, improved flow distribution, and ergonomic actuation mechanisms are becoming meaningful differentiators, especially in environments where seconds matter and the margin for error is small. Products designed to deliver consistent dual-eye coverage, tepid water delivery, and intuitive activation address both compliance goals and practical usability concerns. In laboratory and healthcare-adjacent settings, compact footprints, easy integration with existing wall or bench configurations, and reduced risk of cross-contamination during use are also shaping purchasing preferences.
For manufacturers, the strategic implication is clear: technical features are increasingly tied to specification decisions. Product leadership now extends beyond build quality into performance reliability, ease of testing, and the ability to document compliance over time. This elevates the importance of engineering discipline, validation data, and post-sale support in competitive positioning.
Regulatory expectations and standards enforcement
Regulatory frameworks continue to anchor demand for emergency eyewash infrastructure. Occupational safety requirements mandate suitable facilities for immediate flushing where eyes or body may be exposed to harmful corrosive materials. In practice, this creates a baseline obligation for employers operating in at-risk environments and pushes safety equipment from optional courtesy infrastructure into essential compliance assets.
At the same time, recognized performance and installation guidance continues to sharpen expectations around continuous flow, tepid water delivery, minimum flush duration, and simultaneous eye coverage. Manufacturers and facility managers must therefore consider not only whether a unit exists, but whether it performs correctly under required conditions and can be maintained accordingly. This dynamic reinforces demand for compliant products and services, while also raising the stakes for installation, testing, and recordkeeping practices. In effect, regulation is not only stimulating purchase volume; it is also increasing the cost of non-compliance and rewarding organizations that treat eyewash readiness as an integrated program rather than a point purchase.
Demand-side behavior and organizational risk culture
Buyer behavior is shifting from reactive compliance toward proactive risk management. In chemical-intensive industries, pharmaceutical operations, electronics manufacturing, and oil and gas facilities, the consequences of inadequate first-aid readiness are visible and potentially severe. As a result, safety equipment is increasingly evaluated through the lens of incident mitigation, employee protection, and operational continuity rather than solely regulatory checking.
This cultural shift influences purchasing in several ways. Facilities are more likely to standardize across sites, prefer combination units in high-risk zones, and invest in products that simplify inspection and maintenance workflows. Laboratory environments, in particular, often prioritize immediate accessibility and space-efficient designs that support rapid deployment without disrupting sensitive workflows. In parallel, growing awareness of worker welfare and safety branding can make higher-specification units more attractive, especially where organizations are trying to signal a strong safety culture to staff, auditors, or partners.
Supply chain structure and regional manufacturing dynamics
Cost structure and supply resilience are becoming more prominent in purchasing and product strategy. Manufacturers must navigate raw material pricing, component availability, shipping volatility, and the operational requirements of maintaining consistent quality across different production locations. At the same time, regional sourcing options are shaping buyer considerations around lead times, customization, and support responsiveness.
This environment favors companies that can balance scale with flexibility. For some buyers, domestically produced or well-supported regional products offer perceived advantages in documentation, service proximity, and specification familiarity. For others, competitive pricing and broader portfolio availability from international manufacturers create attractive alternatives, especially in price-sensitive segments or fast-growing industrial markets. The result is a more varied competitive field in which differentiation often comes from a combination of product reliability, service access, and the credibility of compliance support rather than price alone.
Competitive Landscape and Leading Strategies
The market features a diverse set of participants spanning established manufacturers, safety-focused brands, laboratory specialists, distributors, and international producers. This diversity reflects the broad application base of emergency eyewash equipment and the different ways customers evaluate solutions. The presence of multiple competent suppliers also means that competitive advantage depends heavily on execution: product design, compliance alignment, service coverage, and go-to-market clarity.
Parts Washer Market
Strategic positioning among leading participants
Several companies illustrate the range of successful strategic approaches in the market.
Haws Corporation has built a strong identity around flushing performance and application-specific engineering. Its emphasis on advanced rinsing technology for industrial, laboratory, and healthcare settings positions it as a solution provider for buyers who prioritize performance consistency and specialized use cases. This approach helps the company compete on specification quality rather than solely on price, particularly in environments where superior flushing performance is directly tied to safety outcomes.
Guardian Equipment Company is widely recognized for emergency eyewash and shower equipment that covers wall-mounted, pedestal-mounted, and combination configurations. Its alignment with ANSI/ISEA Z358.1 and OSHA expectations gives buyers a straightforward compliance narrative, which is valuable in procurement environments where standardization and audit readiness matter. The breadth of mounting options and unit types also supports flexibility across facility layouts and risk zones.
Bradley Corporation focuses on industrial emergency eyewash stations, safety showers, and combination units with customizable features for high-risk chemical exposure areas. This positions the company well in environments where exposure risk is significant and where specifiers want solutions that can be adapted to specific operational conditions. Customization capability can be a decisive factor when standard off-the-shelf configurations do not fully match site requirements or when facilities seek to consolidate safety equipment specs across complex installations.
Speakman Company offers plumbed and portable eyewash stations along with replacement parts and safety showers. This combination of product supply and parts availability supports longer-term customer relationships by addressing the maintenance and replacement cycle. For many end users, ongoing service access and parts availability are as important as the initial purchase, especially when compliance testing and operational readiness must be sustained over time.
Haws Safety Products under Honeywell brings the recognizable Fendall® brand into industrial and laboratory settings with eye wash stations and cartridges designed for immediate flushing. The brand and cartridge-based approach can resonate with buyers looking for predictable performance, simplified resupply, and familiarity across multiple sites. In laboratory contexts especially, compact cartridge-based solutions may offer a practical balance between readiness and infrastructure demands.
Hughes Safety Company designs ANSI-compliant eyewash stations, self-contained units, and emergency showers for global industrial and workplace use. Its international orientation and compliance-focused portfolio make it relevant for organizations operating across multiple jurisdictions or seeking a consistent safety equipment standard across global facilities. For multi-site enterprises, that consistency can reduce specification fragmentation and simplify training and maintenance programs.
LOC Scientific targets laboratory eye wash station units designed for immediate emergency rinsing and compliance in research and industrial labs. By concentrating on laboratory-specific needs, it addresses a segment where accessibility, space constraints, and rapid response expectations are particularly acute. Niche focus can be a strong competitive lever when the end user environment has distinct operational requirements and when general-purpose products do not fit as cleanly.
Unicare stands out as a pioneer manufacturer based in India, producing eye/face wash stations and safety showers with in-house engineering for industrial and laboratory applications. This reflects the growing relevance of regional manufacturing capability and self-contained engineering resources. For buyers in emerging industrial markets or those seeking localized supply and support, such providers can offer attractive combinations of price, responsiveness, and application understanding.
EyewashDirect.com operates as a distributor and provider of eyewash stations, safety showers, and repair parts from leading manufacturers. Its role highlights the continued importance of distribution channels in this market. Many buyers prefer consolidated sourcing, technical guidance, and access to multiple brands when specifying safety equipment. Distributors that can combine product breadth with compliance-oriented support often serve as important intermediaries between manufacturers and end users.
Sysbel Manufacturing, based in China, supplies laboratory and industrial eye wash systems, including emergency eyewash solutions for chemical splash protection. Its presence underscores the growing influence of international manufacturers in both laboratory and industrial segments, particularly where cost competitiveness, export capability, and expanding portfolio range align with buyer needs.
How the competitive structure is evolving
The market is neither highly concentrated nor fragile. The competitive share distribution suggests room for multiple winners, with leadership determined by product relevance, service quality, and specification influence rather than by scale alone. Over time, three evolutionary patterns are likely to persist.
Consolidation through capability, not just acquisition. Some tightening may occur as larger platforms strengthen their safety portfolios or as distributors integrate broader product lines. However, meaningful consolidation will likely be driven by the desire to offer more complete compliance, service, and specification support rather than by eliminating competition purely for market share.
Segmentation by application and performance tier. As buyers become more sophisticated, the market will continue to differentiate between baseline compliance units and higher-performance or specialized solutions. Manufacturers that can clearly articulate why a given design is better suited to a specific environment—chemical processing areas, laboratory benches, outdoor sites, or multi-hazard work zones—will have stronger positioning.
Entry and expansion from regional and international suppliers. New and expanding suppliers can gain traction by offering competitive alternatives in specific geographies or application niches. This creates both opportunity and pressure for incumbents to defend specification relationships, demonstrate reliable performance, and maintain strong service networks.
Future Trends and What They Mean for Opportunities
Over the next three to five years, the eye wash station market is likely to be shaped by trends that blend compliance, technology, and operational practicality. These trends are not speculative shifts; they are extensions of current pressures and buyer priorities.
Trend 1: Compliance-as-program instead of compliance-as-equipment
Emergency eyewash readiness will increasingly be treated as an ongoing operational program rather than a one-time installation decision. That means greater emphasis on testing routines, documentation, activation reliability, solution or cartridge management, and user training. For suppliers, this opens opportunities in service, replacement parts, inspection support, and products designed to make compliance easier to sustain. For buyers, it argues for selecting equipment and partners that reduce administrative and maintenance friction over the asset lifecycle.
Trend 2: Performance features become default purchasing criteria
As the market matures, features that improve flushing effectiveness, speed of access, temperature control, and ease of use are likely to move from differentiators to expected attributes in many segments. This will reward manufacturers with clear engineering advantages and penalize those competing only on price in specification-driven environments. The commercial opportunity lies in translating technical performance into practical outcome language that resonates with safety managers, facility engineers, and procurement teams.
Trend 3: Broader application diversification and regional growth paths
Demand will continue to spread across chemical, pharmaceutical, electronics, oil and gas, and other industrial or laboratory environments, but the pace and mix will vary. In some regions, expanding industrial activity and laboratory build-outs will support stronger volume growth. In others, replacement cycles and compliance upgrades will be the main driver. This unevenness creates targeted opportunities: companies that align product portfolios with high-exposure segments and regional demand patterns can capture disproportionate relevance in the markets that matter most to them.
PW Consulting
Potential risks and uncertainties
Several uncertainties deserve attention. Regulatory expectations or interpretation can shift, affecting specification requirements and maintenance burdens. Economic cycles may pressure capital spending, particularly among smaller operators or in segments where safety equipment competes with more immediate operational priorities. Supply chain disruptions or input cost volatility can affect margins and delivery reliability. In addition, if buyers over-emphasize lowest initial cost, the market may experience pressure on quality differentiation and service investment. Companies that depend on a narrow product range or on a single geography may also face greater exposure if demand patterns shift unexpectedly.
Strategic Actions for Decision Makers
Different participants should approach the market with different priorities, but several actionable themes apply across roles.
For manufacturers and product developers, clarity of application focus is essential. Rather than competing broadly on volume alone, define where your design advantages actually matter—whether that is flushing performance, laboratory compactness, combination-unit flexibility, cartridge-based resupply, or serviceability. Invest in the documentation, validation, and support materials that help specifiers justify selection during procurement reviews. In parallel, treat maintenance and parts availability as part of the product story, because long-term compliance depends on them.
For investors and strategic planners, the market offers steadier demand characteristics than many discretionary industrial categories, but the best opportunities are likely to come from companies with defensible positioning in specification-driven segments. Look for participants that can demonstrate consistent compliance alignment, meaningful product distinction, and reliable routes to end users through distribution, service, or direct enterprise relationships. Capital allocation should favor structures that can withstand pricing pressure while still investing in performance and support.
For procurement teams and facility operators, the strongest buying decisions will come from evaluating total ownership impact rather than unit price alone. That includes installation requirements, testing burden, water quality considerations, cartridge or solution replacement logistics, replacement part availability, and the consistency of the solution across multiple sites. Where possible, standardize specifications to reduce training and maintenance complexity, and ensure that selected units genuinely match the exposure profile of each zone rather than defaulting to a single model across all areas.
Across all of these roles, timely and detailed market intelligence matters because the eye wash station market is not driven by a single force. It is shaped by overlapping regulation, technical expectations, application needs, and regional dynamics. Decisions made without a clear view of those layers can lead to over-investment in the wrong product tier, missed specification opportunities, or insufficient attention to service and compliance sustainability. The broader market trajectory is constructive, but the real value lies in understanding where growth is concentrated, which product attributes are becoming non-negotiable, and how competitive advantage is being earned on the ground.
Conclusion
The eye wash station market is expanding along a stable, compliance-anchored path, with growth reinforced by industrial activity, laboratory demand, and the continued institutionalization of workplace safety programs. Yet the most important developments are not simply the headline revenue figures. They are the shifts in how products are specified, maintained, and justified; the increasing importance of performance and usability; and the growing influence of service, distribution, and regional manufacturing in shaping buyer choices. Participants that treat eyewash readiness as a long-term operational commitment—and build products, bundles, and relationships accordingly—are best positioned to benefit from the market's next phase of growth.
For detailed analysis of this topic, please visit the official page: Eye Wash Station Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
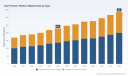
Navigating the Karl Fischer Titrators Market: Strategic Trends and Commercial Opportunities Through 2032
The Karl Fischer titration market has entered a phase of sustained expansion, driven by tightening quality standards, evolving regulatory expectations, and the growing need for precise moisture determination across critical industrial and life sciences applications. Valued at approximately $230 million in 2025, the market has grown consistently from its 2020 baseline, reflecting a compound annual growth rate of 5.5 percent through the forecast horizon ending in 2032. By the close of the projection period, revenue is expected to surpass $335 million, underscoring a steady but structurally shifting demand profile. This trajectory is not merely a function of incremental adoption; it reflects a broader transformation in how organizations approach analytical chemistry, compliance, and operational efficiency. The market's resilience amid macroeconomic fluctuations suggests that moisture analysis has transitioned from a optional quality control step to an embedded requirement across regulated and high-stakes production environments.
Yet expansion alone does not capture the strategic reality facing manufacturers, investors, and procurement leaders. The market is navigating several inflection points that will determine which players capture disproportionate value and which face margin compression or relevance erosion. Understanding these dynamics requires moving beyond headline growth figures and examining the underlying technological, regulatory, and competitive forces reshaping the landscape.
PW Consulting
Market Landscape and Core Challenges
A Market Shaped by Concentration and Capability Gaps
The Karl Fischer titrators market remains moderately concentrated, with the top three participants capturing roughly 70 percent of total revenue and the leading five firms accounting for approximately 85 percent. This concentration reflects the high technical barriers to entry, the importance of reagent ecosystems, and the entrenched procurement relationships within pharmaceutical, chemical, and regulated manufacturing environments. While concentration typically signals stability, it also masks underlying fragmentation in application-specific needs, regional adoption curves, and the widening gap between legacy benchtop systems and next-generation automated or connected platforms. Organizations that continue to treat Karl Fischer titration as a commoditized measurement tool risk underestimating the strategic weight of calibration integrity, data traceability, and operator workflow optimization.
Challenge 1: Balancing Precision with Operational Efficiency
One of the most persistent tensions in the market is the trade-off between measurement precision and throughput. Traditional titration workflows, while highly accurate, often require skilled operators, manual reagent handling, and frequent titer verification. In high-volume environments, these requirements translate into labor intensity, inconsistent turnaround times, and elevated risk of human error. The pressure to increase sample throughput without compromising compliance-grade accuracy is pushing laboratories and production teams to reevaluate their instrumentation strategies. Companies that fail to integrate automation, sample handling, or streamlined calibration routines will find their solutions increasingly misaligned with the operational tempo of modern quality and process labs.
Challenge 2: Regulatory Complexity and Data Integrity Expectations
The regulatory environment surrounding moisture analysis has become more demanding, particularly in pharmaceutical and biotechnology applications where data integrity, auditability, and instrument validation are non-negotiable. Compliance with frameworks such as FDA 21 CFR Part 11 andGood Manufacturing Practice expectations requires more than accurate titration results; it demands secure data handling, version-controlled methods, and traceable calibration records. At the same time, emerging cybersecurity and resilience requirements, including the EU Cyber Resilience Act, are extending compliance obligations into laboratory equipment ecosystems that were historically treated as isolated analytical tools. For manufacturers and end users alike, this creates a dual burden: maintaining analytical rigor while implementing stronger software governance, access controls, and remote diagnostic safeguards.
Challenge 3: Reagent Stability and Supply Chain Reliability
Moisture titration depends heavily on reagent quality and consistency, yet standard solvents and titration reagents introduce operational variability that can quietly erode measurement confidence. Methanol-based solvents used in volumetric Karl Fischer titration, for example, exhibit gradual titer degradation that necessitates regular verification and corrective adjustments. Approximately a 5 percent titer decrease per year is typical, meaning that laboratories must build routine titer checks into their workflows or risk systematic measurement drift. This reality complicates cost planning, increases consumable management overhead, and underscores the importance of reagent formulation innovation. In an era where supply chain volatility can disrupt laboratory operations, the ability to standardize reagent performance and reduce frequent titer corrections is becoming a meaningful differentiator rather than a logistical footnote.
Laboratory Water Purifier Market
Key Drivers Reshaping the Market
Technological Innovation and the Shift Toward Intelligent Titration
Technological advancement is the most visible force propelling market evolution. The industry is moving beyond standalone titration units toward integrated systems that combine faster detection algorithms, automated sample introduction, and smarter calibration logic. Recent product introductions illustrate this shift clearly. In mid-2024, a major analytical instrumentation provider launched a volumetric Karl Fischer titrator featuring a fast-forecasting amperometric algorithm alongside an oven autosampler designed for high-throughput water analysis. The combination of improved signal processing and automated sample handling directly addresses the throughput-versus-precision tension described earlier. A few months later, another manufacturer extended its titrator lineup by upgrading control firmware and electrode systems to improve measurement stability, highlighting how incremental engineering refinements can yield meaningful gains in repeatability and operator confidence.
By early 2025, the trend toward intelligence and remote support became even more pronounced when a leading Swiss instrumentation firm released a titration platform integrating AI-based calibration and remote diagnostics. This move signals a broader industry recognition that instrumentation value is increasingly defined by software-enabled accuracy, predictive maintenance, and reduced downtime rather than mechanical design alone. In parallel, a major scientific instrumentation company introduced a portable Karl Fischer moisture analyzer with wireless connectivity and ruggedized construction for field applications, expanding the addressable use cases beyond controlled laboratory environments into on-site production, logistics, and remote quality checks. These developments collectively point to a market where analytical performance, connectivity, and deployment flexibility are converging.
Regulatory and Compliance Pressures as Adoption Accelerators
Regulatory expectations are not merely constraints; they are powerful adoption drivers. In regulated industries, the requirement for validated methods, documented data integrity, and instrument traceability encourages organizations to upgrade from informal or aging titration setups to compliant, auditable systems. The emphasis on data security and operational resilience is also reshaping procurement criteria. As laboratory operations face updated GMP expectations and broader cybersecurity mandates, buyers are increasingly prioritizing instruments that support secure data handling, controlled user access, and firmware or software update pathways that do not compromise validated states. This regulatory momentum benefits manufacturers that design compliance into their platforms from the outset, while creating friction for those relying on retrofitted or opaque software architectures.
Evolving Demand Patterns Across Regulated and Process Industries
Demand is being shaped by a combination of quality intensification and broader application expansion. In pharmaceutical and biotechnology environments, moisture specification control remains critical for product stability, formulation integrity, and process validation, sustaining steady demand for high-precision titration solutions. In the chemical industry, moisture monitoring influences reaction control, catalyst performance, and product grading, reinforcing the need for reliable titration across both laboratory and process-adjacent settings. Food and beverage applications, while smaller in relative terms, continue to drive adoption where moisture content affects shelf life, sensory properties, and regulatory compliance. Beyond these core segments, additional application areas contribute to demand diversification, including specialized industrial testing and routine quality assurance workflows.
What matters strategically is not just the existence of these application segments, but the changing expectations within them. End users increasingly want solutions that reduce hands-on time, simplify reagent management, and integrate cleanly into existing laboratory or production data environments. The organizations winning adoption are those that align instrumentation capabilities with practical workflow outcomes rather than competing solely on specification sheets.
Supply Chain, Consumables, and Cost Structure Dynamics
Cost structures in the Karl Fischer titrators market are influenced by both hardware economics and ongoing consumable requirements. Instrument pricing remains important, but total cost of ownership is increasingly defined by reagent consumption, titer verification frequency, maintenance intervals, and the operational cost of downtime. The stability of standard methanol solvents and the recurring need for titer checks illustrate how consumable behavior can affect laboratory budgeting and staffing. At the same time, efforts to develop more stable or eco-friendly titration reagents are gaining traction. A notable partnership in mid-2025 between a major instrument manufacturer and a leading chemical producer focused on co-developing eco-friendly titration reagents for Karl Fischer applications, signaling that reagent innovation is becoming a strategic pillar rather than a back-end supply detail. For end users, better reagent stability translates into fewer corrective checks and more predictable consumable planning; for manufacturers, it opens avenues for differentiated reagent ecosystems and longer service intervals.
Competitive Landscape and Strategic Positioning
Established Leaders and Their Differentiation Plays
The competitive field is anchored by a mix of globally established analytical instrumentation firms and specialized manufacturers with strong regional or application-specific footprints. One of the leading Swiss providers has built its position around a broad portfolio spanning volumetric and coulometric platforms, including models designed for liquid, solid, and gaseous sample types. Its recent emphasis on AI-assisted calibration and remote diagnostics reflects a strategy centered on reducing operational uncertainty and extending service reach beyond the laboratory door. By embedding intelligence into calibration and support workflows, the company aims to reinforce trust in measurement results while lowering the hidden costs of troubleshooting and repeat analysis.
A major U.S.-based instrumentation player has pursued a parallel but distinct path, focusing on automatic titration systems and high-precision moisture analysis workflows. Its product lineup includes volumetric and coulometric options, complemented by oven autosampling capabilities that support higher throughput and broader sample handling. The strategic logic here is clear: by pairing precise titration chemistry with automation and robust application support, the company addresses the needs of laboratories that must handle larger sample volumes while maintaining compliance-grade data quality. This automation-led positioning is particularly relevant in environments where operator time and method consistency are under pressure.
Another prominent European analytics group has strengthened its presence through automatic titration platforms engineered for both volumetric and coulometric water determination, with connectivity-oriented design elements such as integrated interface sockets for expanded system integration. This connectivity focus aligns with the broader industry movement toward instruments that can sit within larger analytical or laboratory data ecosystems rather than functioning as isolated devices. Meanwhile, a Japanese manufacturer has carved out a recognizable position through dedicated moisture titration series and proprietary reagent formulations, emphasizing precision and application-specific reliability. Its product range spans coulometric and volumetric models designed for automated moisture analysis, reinforcing the importance of matched reagent-instrument systems in delivering consistent results.
Moisture Analyzer Market
U.S.-based specialty manufacturers have also maintained meaningful positions, particularly where application focus sharpens competitive advantage. One company has concentrated on coulometric titrators for petroleum, petrochemical products, oils, and solvents, an application segment where moisture control is tightly linked to product quality and processing efficiency. Another major water analysis and instrumentation supplier offers automatic Karl Fischer titrators suited to both laboratory and process applications, reflecting the value of versatile platforms that can bridge analytical and near-process environments. A further U.S. provider emphasizes customizable volumetric titration setups for laboratory moisture analysis, appealing to organizations that prioritize flexibility in method configuration and sample handling.
In Japan, another electronics and instrumentation manufacturer has contributed to the market with moisture titrators supported by dedicated reagent systems designed for industrial sample analysis, underscoring the continued relevance of regional engineering expertise and application-tuned reagent chemistry. At the same time, Chinese manufacturers have been expanding their presence with cost-competitive titrator platforms that combine practical specifications with upgraded firmware and electrode systems. Recent updates from one Chinese manufacturer highlighted improved measurement stability through firmware and electrode enhancements, illustrating how emerging competitors are moving beyond price competition toward capability refinement. Another Chinese firm has promoted titrator solutions with defined polarization current and repeatability characteristics, appealing to buyers who need predictable performance at accessible price points.
Market Evolution: Consolidation, Differentiation, and New Entry Points
The competitive landscape is evolving along three concurrent paths. First, established leaders are deepening differentiation through software, automation, and service connectivity rather than hardware novelty alone. The most valuable platforms are increasingly those that reduce operator burden, improve calibration confidence, and support secure, auditable data practices. Second, application specialization remains a viable and often underappreciated route to competitive strength. Companies that tailor their titration platforms, reagents, and workflow support to specific industries or sample types can build durable demand even in a concentrated market. Third, new and expanding entrants are challenging the assumption that advanced titration capabilities are the exclusive domain of large multinational firms. By improving measurement stability, offering practical specifications, and targeting cost-sensitive segments, these players are widening the competitive field and pressuring incumbents to justify premium positioning through demonstrable workflow and compliance benefits.
For buyers and investors, this evolution means that competitive advantage is less about brand familiarity and more about fit: fit between instrument capabilities and sample workflows, fit between reagent systems and verification frequency, and fit between software architecture and regulatory or cybersecurity expectations. The organizations that can articulate and deliver that fit will be best positioned to defend share and expand into adjacent application areas.
Forward Outlook: Three Strategic Trends to Watch
Trend 1: Intelligence and Remote Support as Standard Expectations
Over the next three to five years, AI-assisted calibration, predictive diagnostics, and remote support capabilities are likely to transition from differentiators to baseline expectations in the Karl Fischer titrators market. The recent introduction of platforms featuring AI-based calibration and remote diagnostics, alongside firmware and electrode upgrades aimed at measurement stability, indicates that the industry is already moving in this direction. For manufacturers, this trend creates opportunities to design instruments that reduce downtime, simplify maintenance planning, and improve result consistency across operators and sites. For end users, the commercial implication is clear: instrumentation that supports fewer interruptions, more reliable calibration states, and faster issue resolution can lower the hidden costs of moisture analysis and improve laboratory throughput. The principal risk is that intelligence features become commoditized quickly, shifting the competitive battleground toward data security, integration depth, and long-term service economics rather than feature presence alone.
Trend 2: Compliance and Cybersecurity as Procurement Filters
Regulatory and cybersecurity requirements will increasingly shape purchasing decisions, particularly in regulated industries and multi-site laboratory environments. Compliance with data integrity expectations and broader resilience mandates is pushing organizations to evaluate instruments not only on analytical performance but also on software governance, user access control, validation support, and update management. This trend favors manufacturers that have built compliance-friendly architectures and can provide clear documentation and support pathways. It also creates a practical opportunity for vendors to bundle instrumentation with services that help laboratories maintain validated states while adapting to evolving security requirements. The uncertainty lies in the pace and variability of regulatory interpretation across regions, which may lead to uneven adoption timelines and divergent compliance expectations that complicate global deployment strategies.
Trend 3: Reagent Innovation and Field-Ready Deployment Expanding Use Cases
Two related developments are likely to broaden the market's application base and change how moisture analysis is deployed. First, reagent innovation focused on improved stability and environmental profile is gaining momentum, with partnerships aimed at co-developing eco-friendly titration reagents signaling a longer-term shift in consumable strategy. If these efforts translate into reduced titer drift and more predictable handling, they can lower the operational burden of routine verification and improve cost predictability for end users. Second, the expansion of portable and ruggedized moisture analysis tools with wireless connectivity is extending Karl Fischer-based measurement into field and process-adjacent settings. This opens opportunities in industries where sample transport to a central laboratory creates delays or where on-site decisions depend on rapid moisture data. The commercial opportunity for manufacturers lies in building platforms that combine dependable analytical performance with practical field usability and consumables that hold up under varied operating conditions. The risk is that broader deployment also exposes instruments to more demanding environments, increasing the importance of robustness, training, and support infrastructure.
Strategic Implications for Decision Makers
For Manufacturers and Solution Providers
Positioning should increasingly revolve around workflow outcomes rather than isolated specifications. Investments in automation, smarter calibration logic, electrode and firmware stability, and secure software architecture are likely to yield stronger competitive returns than incremental hardware changes alone. Equally important is the reagent and consumables strategy: improving reagent stability, offering clearer titer management guidance, and aligning reagent formulations with instrument performance can reduce customer friction and create defensible ecosystem advantages. Manufacturers should also prepare for compliance-driven procurement by ensuring that documentation, data handling, and update processes support auditable, validated operations without imposing disproportionate administrative burden on end users.
For Investors and Strategic Planners
The market's growth trajectory is steady, but value creation will be uneven. The most attractive opportunities are likely to emerge where technology, compliance readiness, and application fit intersect. Investors and planners should look beyond top-line growth and assess which companies are building durable advantages through software-enabled reliability, reagent ecosystem strength, and service models that reduce total cost of ownership. Interest in field-deployable and connected moisture analysis also suggests that adjacent use cases may expand demand beyond traditional laboratory settings. At the same time, concentration in the market means that competitive disruptions are more likely to come from capability upgrades by emerging players or from application-specific specialization than from broad-based price wars. Monitoring firmware, electrode, and reagent innovations, as well as partnerships that reshape consumable offerings, will provide early signals of shifting competitive dynamics.
For Procurement and Operations Leaders
Procurement decisions should weigh total cost of ownership more heavily than initial purchase price. Key evaluation criteria should include calibration and titer management burden, automation and sample handling capabilities, data integrity and software governance features, reagent stability expectations, and the vendor's ability to support validated or regulated environments. Where moisture analysis is tied to high-volume workflows or compliance-critical applications, instruments that reduce operator intervention and improve measurement repeatability can deliver meaningful operational savings over time. Procurement teams should also consider deployment context: laboratory-bound systems, process-adjacent setups, and field applications have different robustness, connectivity, and support requirements, and matching the platform to the environment can prevent underperformance and unnecessary service costs.
The Karl Fischer titrators market is entering a period in which analytical precision, operational efficiency, and compliance readiness must advance together. Organizations that treat moisture analysis as a strategic workflow rather than a routine test will be better positioned to capture the value of upcoming technological and regulatory shifts. For those seeking a more detailed breakdown of segmentation dynamics, regional adoption patterns, application-specific demand drivers, and competitive benchmarks to support internal planning, the full research report provides a deeper evidence base and tailored scenario guidance.
For detailed analysis of this topic, please visit the official page: Karl Fischer Titrators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
VCI Anti Rust Paper Market: Why 4.8% CAGR and Hidden Applications Reshape 2032 Outlook
By PW Consulting, 2026-09-21
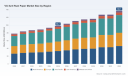
The VCI Anti Rust Paper Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and the Road Ahead
The global VCI anti rust paper market has demonstrated consistent expansion over the past half decade, moving from approximately 78.25 million USD in 2020 to an estimated 98.2 million USD in 2025. This trajectory reflects a compound annual growth rate of 4.8 percent, with projections indicating the market will cross the 136 million USD threshold by 2032. The growth is not merely a function of incremental volume increases but rather a structural shift in how manufacturers, logistics providers, and industrial distributors approach asset protection during storage and transit. Corrosion prevention has evolved from a compliance afterthought into a strategic component of supply chain resilience, quality assurance, and total cost of ownership calculations. Beneath these headline figures lies a market with concentrated positioning and distinct regional and sectoral imbalances. A handful of established players command the majority of market share, with the top three firms accounting for roughly 62.5 percent and the top five reaching 78.2 percent of total revenue. This concentration signals a mature competitive landscape where differentiation, rather than scale alone, determines winners. At the same time, regional demand patterns reveal divergent growth drivers, with developed markets focusing on regulatory compliance and technical performance while emerging economies prioritize cost-effective corrosion protection for expanding metalworking and packaging sectors. Understanding these underlying dynamics is essential for decision makers evaluating market entry, capacity expansion, or supplier relationships.
Structural Challenges Shaping the Market
Several intersecting challenges are forcing the industry to recalibrate its growth assumptions and operational strategies. Recognizing these friction points early allows executives to build more resilient business models rather than reacting defensively when pressures intensify.
One of the most pressing challenges is the tightening regulatory environment around chemical formulations. Environmental and safety directives in major markets are progressively restricting amine-based volatile corrosion inhibitors and phthalate-based plasticizers commonly used in VCI film and paper products. Compliance is no longer a static checkbox; it requires continuous reformulation, testing, and documentation. Companies operating with legacy chemistries face escalating scrutiny, while those that proactively transition to nitrite-free, renewable, and fully repulpable formulations are positioning themselves to capture procurement mandates from increasingly sustainability-conscious buyers.
A second challenge stems from cost inflation across raw material inputs and logistics channels. Amine chemistry feedstocks and transportation expenses have exerted sustained pressure on margin structures for VCI packaging materials. In an environment where end users are highly price-sensitive and alternative barrier solutions remain available, suppliers must balance cost pass-through with value demonstration. The burden falls on manufacturers to articulate how advanced VCI paper reduces total lifecycle costs through reduced damage, lower warranty claims, and extended storage life, rather than competing solely on unit price.
A third structural challenge involves the heterogeneity of end-use requirements. Metal packaging, machinery and equipment, and other industrial applications each impose distinct performance criteria, exposure conditions, and regulatory expectations. A formulation that performs adequately for ferrous metal storage may not satisfy multi-metal protection requirements or extended duration needs. This fragmentation complicates standardization and increases the cost of tailored product development. Companies that fail to align product architectures with specific application profiles risk losing share to competitors offering more precise fit-for-purpose solutions.
Core Drivers Catalyzing Market Evolution
The market's continued expansion is being propelled by a combination of technological innovation, regulatory realignment, shifting demand behaviors, and supply chain restructuring. Each driver reinforces the others, creating compounding effects that reward early movers and penalize laggards.
Technology and chemistry innovation remains the most decisive differentiator. Recent advancements in vapor-phase corrosion inhibition have enabled formulations that deliver extended protection without compromising recyclability or repulpability. The development of VCI nanotechnology on renewable kraft substrates illustrates how performance and sustainability can converge rather than compete. Products that combine expandable cushioning with active corrosion inhibition represent a step change in functional packaging, addressing both mechanical protection and long-term metal preservation within a single consumable. These innovations reduce the need for multiple packaging layers, simplify handling, and improve protection consistency across complex part geometries.
Policy and regulatory pressure is accelerating the transition toward compliant chemistries across key markets. Regulatory frameworks are increasingly mandating nitrite-free formulations and pushing for biodegradable and safer chemical profiles in VCI papers. In parallel, air quality and emission standards are raising compliance costs for amine-based chemistries, making reformulation an operational necessity rather than a discretionary initiative. Companies that treat regulatory evolution as a strategic signal rather than a compliance expense are building portfolios with longer regulatory half-lives and broader geographic applicability.
Demand-side behavior shifts are reshaping procurement priorities. Industrial buyers are placing greater weight on lifecycle performance, environmental footprint, and vendor reliability when selecting corrosion protection solutions. The emphasis has moved beyond immediate cost to include total cost of ownership, risk mitigation, and alignment with corporate sustainability commitments. This shift is particularly pronounced among operators managing high-value machinery, sensitive electronic components, and long-duration storage scenarios, where corrosion-related failures carry significant financial and reputational consequences. Procurement teams are consequently favoring suppliers that can demonstrate consistent performance, transparent chemistry, and documentation supporting waste reduction and material recovery.
Supply chain and cost structure changes are influencing sourcing strategies and manufacturing footprints. Volatility in raw material pricing and freight costs has prompted buyers to diversify suppliers, shorten supply lines where feasible, and prefer partners with localized production or regional distribution capabilities. At the same time, manufacturers are investing in process efficiencies and formulation optimization to absorb input cost pressures without eroding margins. The result is a market where responsiveness, reliability, and formulation flexibility are becoming as important as base pricing.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a core group of specialized manufacturers whose strategic approaches illuminate the pathways to sustained advantage. While market concentration remains high, the nature of competition is shifting from broad product availability toward targeted technical value, regulatory readiness, and application-specific performance.
Cortec Corporation has built its positioning around renewable, recyclable, and fully repulpable VCI chemistry applied to kraft paper substrates. Its coated VCI papers are designed for both ferrous and non-ferrous metal protection across storage and shipping contexts. The strategic emphasis on a circular-material profile aligns with procurement teams seeking to reduce waste streams and simplify end-of-life handling while maintaining active corrosion inhibition.
Daubert Cromwell has focused on nitrite-free formulations and compliance-oriented product lines, including VCI papers aligned with recognized military specifications for multi-metal corrosion protection. This compliance-centric posture appeals to sectors where documentation, standardization, and chemical safety are non-negotiable, such as defense, aerospace-adjacent supply chains, and regulated industrial manufacturing.
ZERUST Solutions offers VCI kraft papers and reinforced or poly-coated variants that provide vapor-phase protection for ferrous metals. The breadth of substrate options enables coverage across different handling conditions and exposure profiles, allowing the company to address varied industrial requirements without fragmenting its core technology.
Volatile Corrosion Inhibitors (VCI) Packaging Material Market
Intertape Polymer Group emphasizes extended-duration protection, with nitrite-free VCI saturated kraft papers that support multi-metal protection over long storage intervals. The ability to specify protection duration is a meaningful commercial lever in logistics-heavy environments where parts may remain in transit or warehousing for extended periods.
Antirusting Anti Rust Agents Market
Armor Protective Packaging has combined nanotechnology-enabled corrosion inhibition with renewable kraft substrates, including expandable cushioning formats that integrate mechanical protection and VCI function. Its recent collaborative launch of an expandable VCI paper concept underscores a broader industry move toward multi-functional packaging that reduces material complexity while improving performance.
Rust-X has concentrated on durability attributes such as tear and puncture resistance through super laminated VCI papers. For operations handling heavy, irregular, or high-abrasion metal components, mechanical robustness is a critical purchase criterion, and this focus differentiates the offering in applications where standard paper formats may be prone to failure.
PW Consulting
Across these players, several strategic themes emerge. First, differentiation is increasingly rooted in chemistry transparency, regulatory alignment, and sustainability credentials rather than price alone. Second, product architectures are becoming more application-specific, with reinforcement, coating, and saturated formats tailored to distinct handling and exposure conditions. Third, the market is experiencing incremental convergence between mechanical protection and active corrosion inhibition, reducing the need for layered packaging and improving total system performance.
The evolutionary trend in market structure points toward selective consolidation and continued specialization. Established players with strong technical portfolios and regulatory readiness are well positioned to absorb niche capabilities or expand into adjacent format segments. At the same time, new entrants may find opportunity in highly targeted niches, such as formulations for specific metal alloys, biodegradable variants, or region-specific compliance packages. Broad, undifferentiated entry is less viable in a market where performance validation and regulatory familiarity carry substantial weight.
Forward Outlook: Three Trends to Watch
Looking ahead across the next three to five years, several trends are likely to shape investment, sourcing, and product strategy in the VCI anti rust paper market.
Accelerated reformulation toward compliant, renewable chemistries will intensify as regulatory scrutiny deepens and buyer sustainability requirements become more explicit. Companies that proactively retire higher-risk chemistries and develop nitrite-free, biodegradable, or fully repulpable solutions will gain preferential access to procurement cycles in regulated and sustainability-focused segments. The commercial opportunity lies not only in compliance but in the ability to market a clear environmental and safety narrative that reduces buyer risk and aligns with corporate responsibility goals. The associated risk is execution lag; firms that delay reformulation may face sudden exclusion from bids that specify chemical restrictions or biodegradability criteria.
Multi-functional packaging will continue to gain share as operators seek to simplify material stacks and improve protection consistency. Integrating cushioning, barrier properties, and vapor-phase corrosion inhibition into a single paper-based solution reduces handling complexity and can lower total packaging cost even when per-unit pricing is higher. This trend opens opportunities for manufacturers that can combine mechanical robustness with active inhibition and for buyers who can rationalize SKU counts and supplier relationships. The risk is that over-functionalization may increase cost or compromise recyclability if substrate choices are not carefully managed, so technical validation remains essential.
Regional divergence in demand and compliance requirements will create both fragmentation and arbitrage opportunities . Mature markets will continue to emphasize regulatory conformity, documentation, and lifecycle performance, while faster-growing regions will balance performance with affordability and supply reliability. Suppliers with flexible formulation platforms, localized distribution, and the ability to tailor products to regional regulatory baselines will be better positioned to capture cross-market growth. The uncertainty lies in the pace and symmetry of regulatory adoption across jurisdictions, which can shift competitive advantage quickly if one region moves ahead of others in restricting specific chemistries.
Strategic Considerations for Decision Makers
For manufacturers and product developers, the priority is to align formulation roadmaps with regulatory trajectories and application-specific performance needs. Investing in nitrite-free, renewable, and repulpable chemistries while maintaining protection duration and mechanical robustness will expand addressable demand and reduce regulatory exposure. Equally important is building validated documentation and testing protocols that allow procurement teams to verify performance claims and meet internal sustainability thresholds. Companies that can articulate a clear link between chemistry, protection performance, and end-of-life handling will be better equipped to justify value to buyers who are increasingly scrutinizing total cost rather than unit price. For investors, the market rewards businesses with defensible technical differentiation and resilient compliance postures. Concentration in the top tier suggests that competitive advantage is often tied to formulation IP, regulatory readiness, and application breadth rather than scale alone. Due diligence should therefore emphasize chemistry portfolios, reformulation capability, certification and documentation strength, and the ability to serve multi-metal and extended-duration requirements. Capital allocation toward companies with clear pathways to compliant, multi-functional products and regional flexibility is likely to offer more durable exposure than bets on undifferentiated capacity expansion. For procurement and supply chain leaders, the focus should shift from transactional price comparison to total value evaluation. Evaluating VCI paper suppliers against criteria such as multi-metal compatibility, protection duration, mechanical durability, chemical compliance, and recyclability can reduce downstream risk and improve consistency across storage and shipping operations. Diversifying supply sources while prioritizing vendors with strong regulatory alignment and transparent chemistry reduces vulnerability to reformulation disruptions and regional compliance shifts. Negotiations are more effective when underpinned by performance specifications that reflect actual exposure conditions rather than generic packaging requirements. The pace of regulatory change, input cost volatility, and evolving buyer expectations means that static market assumptions quickly become outdated. Decision makers benefit from continuously updated intelligence on formulation shifts, competitive moves, and regional compliance baselines to avoid misaligned sourcing or investment choices. Detailed segment-level data, company-level profiling, and scenario analysis can sharpen planning and reveal where to concentrate resources for the highest return.
Completing the full analysis provides access to granular segment breakdowns, regional demand profiles, competitive benchmarking, and forward scenarios that extend beyond the directional view presented here. For teams evaluating market entry, supplier selection, formulation investment, or portfolio strategy, that additional depth supports more precise prioritization and reduces the uncertainty inherent in a rapidly evolving corrosion protection market.
For detailed analysis of this topic, please visit the official page: VCI Anti Rust Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Airbag Market to Hit $29.79B by 2032: Decoding the 7.25% CAGR Growth and Asia Pacific's Dominance Shift
By PW Consulting, 2026-09-21
Navigating the Airbag Market: Strategic Trends and Commercial Opportunities (2026–2032)
The global airbag market has entered a maturation phase characterized by steady expansion, technological diversification, and shifting regulatory pressures. Valued at approximately $18.28 billion in 2025, the sector has grown consistently from $12.93 billion in 2020, reflecting a compound annual growth rate of 7.25 percent through 2032. This trajectory is not merely a function of rising vehicle production; it signals a structural realignment in how occupant and external safety are engineered, regulated, and commercialized. For executives, investors, and procurement leaders, the next seven years will reward those who align product strategy with evolving safety expectations, supply chain resilience, and regional regulatory divergence.
Beneath the headline growth figures lies a market exhibiting pronounced concentration and regional asymmetries. The top three suppliers capture roughly 62.8 percent of revenue, while the top five account for 74.5 percent, indicating an environment where scale, established automaker relationships, and integrated component capabilities create durable moats. At the same time, the market’s composition reveals where value creation is accelerating: frontal systems remain the largest category, side airbags command significant share, and knee/curtain configurations are expanding as vehicle architectures grow more complex. On the application side, passenger vehicles dominate revenue generation, commercial vehicles represent a stable but slower-growing segment, and electric vehicles are carving out a distinct growth corridor as platform designs and battery-related safety considerations reshape module requirements. Understanding these structural patterns is essential before evaluating the forces that will shape competitive positioning through the end of the decade.
Market Landscape and Core Challenges
The airbag market’s expansion is anchored in a multi-year upward trajectory, but growth alone does not guarantee profitability or strategic advantage. Several structural frictions are forcing suppliers and automakers to recalibrate how they design, source, and deploy safety systems.
Regulatory Fragmentation and Compliance Complexity
Safety regulations are no longer converging globally; they are diverging in ways that complicate platform standardization. In the United States, the Department of Commerce’s January 2025 final rule on connected-vehicle information and communications technology supply chains has introduced new compliance pathways for components tied to vehicle electronics and embedded safety systems. While the rule targets ICTS sourcing, its ripple effects extend to airbag control units, sensing integration, and supplier qualification processes, particularly for companies with cross-border manufacturing footprints. This regulatory layer adds cost and timeline uncertainty, especially for suppliers navigating dual requirements across North American, European, and Asian markets.
Raw Material Volatility and Cost Structure Pressures
Airbag manufacturing remains sensitive to polymer and chemical input pricing. Nylon 6,6, a critical material for airbag fabric and structural components, experiences periodic price fluctuations driven by production capacity shifts and downstream demand dynamics. Ascend Performance Materials’ ongoing support of nylon 6,6 production for airbag applications underscores how tightly woven the material supply chain is. When feedstock costs move, suppliers must decide whether to absorb margin compression, renegotiate tier agreements, or accelerate material substitution programs. The companies that treat material strategy as a continuous optimization exercise rather than a periodic sourcing task will preserve competitiveness during cyclical price swings.
Waste Management and Recall-Related Liability
End-of-life handling and recall scenarios introduce operational and reputational risk that is often underestimated in top-line planning. Hazardous airbag waste falls under RCRA hazardous waste regulations, and the U.S. EPA’s October 2025 interim final rule on safe management of recalled airbags adds conditional exemptions and procedural requirements that affect how manufacturers, dealers, and recyclers manage inventory and field returns. For suppliers, this means that compliance does not end at the point of sale; it extends into reverse logistics, documentation, and cooperative recall response. Firms that build these processes into their operating models reduce exposure to regulatory friction and strengthen customer trust during safety interventions.
Taken together, these challenges point to a market where scale alone is insufficient. Growth will increasingly be captured by organizations that can manage regulatory complexity, stabilize input costs, and integrate safety with broader mobility ecosystems rather than treating airbags as isolated passive components.
Key Drivers Shaping Market Dynamics
The market’s forward trajectory is being pulled by three interconnected forces: technology innovation that expands the definition of protection, regulatory and policy shifts that raise baseline expectations, and demand-side behavior that blends occupant safety with external collision mitigation. A fourth driver, supply chain restructuring around cost and resilience, is determining who can profitably scale new configurations.
Technology Innovation and the Expansion of Protection Boundaries
Airbag technology is moving beyond traditional occupant compartments into external protection, specialty applications, and smarter deployment logic. Autoliv’s April 2026 launch of a second-generation cyclist-pedestrian protection airbag illustrates this shift. By covering a larger area to improve head protection during external collisions, the product reorients airbag value propositions around vulnerable road users and vehicle-to-environment interactions. Similarly, Daicel’s May 2026 wearable airbag, developed with NIIST and the Sony Acceleration Platform, extends automotive safety technology into elderly fall mitigation. These launches are not isolated product news; they signal that safety technology portfolios are becoming more modular and application-agnostic, creating pathways to non-automotive revenue streams and cross-market brand leverage.
Policy and Regulatory Pressure Raising Baseline Safety Expectations
Regulators continue to tighten occupant protection expectations, and vehicle safety ratings increasingly influence purchase decisions. The introduction of Volvo Trucks’ industry-first standard integrated side curtain airbag in February 2026, recognized as a HDT 2025 Top 20 Product, demonstrates how regulatory and rating-driven pressure can push advanced configurations from optional features to standard equipment in commercial segments. When flagship players normalize a technology, the threshold for competitor adoption rises, and procurement teams must plan for broader specification coverage across fleets. Policy momentum therefore operates as both a compliance requirement and a competitive cascade, accelerating adoption curves that might otherwise lag behind passenger-car segments.
Demand-Side Shifts in Consumer and Fleet Behavior
Buyers are increasingly treating safety as a differentiated purchase criterion rather than a standardized expectation. In passenger vehicles, this translates into demand for more comprehensive curtain, knee, and side configurations as cabin layouts evolve and seating positions change. In commercial vehicles, fleet operators are prioritizing driver protection and total cost of ownership, which makes standard safety packages more attractive when they reduce incident-related downtime and insurance exposure. Electric vehicles add another layer: platform architectures, battery placement, and weight distributions alter deployment zones and module placement logic, prompting suppliers to adapt designs to EV-specific packaging constraints. As a result, demand is no longer uniform across vehicle types; it is fragmenting by use case, platform, and operational profile.
Worldwide Belt Type Fall Protection Airbag Market
Supply Chain and Cost Structure Realignment
The supply base is responding to material volatility, geographic sourcing constraints, and the need for faster engineering feedback loops. Suppliers that integrate inflator technology, fabric engineering, and module assembly under coordinated development cycles can reduce lead-time variability and better manage cost transitions. At the same time, regulatory actions around ICTS and connected systems are encouraging regionalization and dual-sourcing strategies, particularly for electronics-adjacent safety components. The practical implication is that cost leadership is increasingly derived from integration, regional presence, and engineering responsiveness rather than sheer procurement volume alone.
These drivers converge on a single insight: the airbag market is expanding not just because more vehicles are being sold, but because protection is becoming broader in scope, more standardized at higher performance levels, and more dependent on integrated engineering capability.
Competitive Landscape and Strategic Positioning
The market’s concentration profile favors incumbent suppliers with global footprints, established automaker partnerships, and multi-product capabilities across inflators, modules, and complementary restraint systems. A review of the leading players shows how different strategic postures are being used to defend share and capture growth.
Incumbent Scale and Integrated Capabilities
Autoliv’s positioning as the world’s largest automotive safety supplier gives it broad exposure across airbags, seatbelts, and passive safety systems, enabling coordinated engineering across restraint categories. This scale supports platform sharing, global volume leverage, and the ability to introduce advanced external-protection concepts such as the cyclist-pedestrian airbag. Joyson Safety Systems occupies a similarly broad mobility safety position, extending beyond automotive into non-automotive markets, which diversifies revenue and creates cross-application learning loops. ARC Automotive focuses more narrowly on inflators for a wide range of airbag types, a specialization that makes it a critical component partner and allows it to influence deployment performance at a foundational level. Daicel brings chemical and plastics expertise to inflators, pyro-fuses, and related safety technologies, positioning it at the intersection of material science and safety performance.
Regional and Ecosystem-Embedded Players
Toyota Boshoku and Hyundai Mobis illustrate how supplier strength can be amplified by close ties to vehicle platforms. Toyota Boshoku’s interior systems capabilities and Hyundai Mobis’s module and safety technology portfolio benefit from group-aligned development cycles, which can shorten validation timelines and improve packaging fit. Nihon Plast and Toyoda Gosei add depth in safety components and interior/safety integration, while ZF Friedrichshafen and Continental contribute broader automotive technology portfolios that include occupant protection systems alongside seating and chassis-related competencies. These players demonstrate that differentiation is not limited to volume; it can also come from platform alignment, component specialization, and technology adjacency.
Strategic Differentiation and Competitive Evolution
The competitive evolution in this market is moving along two tracks. On one track, consolidation and partnership activity reinforce the advantages of scale, global service networks, and multi-component integration. On the other, differentiation is increasingly found in application expansion, such as external protection and wearable safety concepts, and in the ability to adapt to commercial vehicle standardization and EV packaging requirements. New entrants face a steep climb unless they bring a defensible technology niche, a distinctive material or inflator advantage, or a strong regional relationship model. The more probable competitive dynamic is continued concentration at the top, layered with selective specialization where performance, application scope, or regional compliance create meaningful separation.
For decision-makers, the practical takeaway is that supplier selection and partnership strategy should account for more than unit price. Engineering collaboration, regional compliance readiness, inflator and module integration depth, and the ability to support nonstandard configurations are becoming decisive factors in long-term value capture.
Forward Outlook: Trends and Commercial Implications
Looking ahead three to five years, three trends are likely to shape where value is created and where risk accumulates.
Trend One: External and Vulnerable-Road-User Protection Becomes a Commercial Priority
External protection concepts are moving from experimental to productized, as evidenced by cyclist-pedestrian airbag developments and broader attention to vehicle-to-environment interactions. This trend opens opportunities in advanced module designs, sensing-adjacent integration, and region-specific safety packaging. The commercial upside lies in differentiated safety claims, rating advantages, and potential regulatory alignment in markets that increasingly weigh external impact performance. The uncertainty is execution: external protection requires careful validation, packaging trade-offs, and cost discipline to avoid becoming a low-volume niche.
Trend Two: Standard Safety Packages Expand in Commercial and Specialty Segments
Commercial vehicle adoption of integrated side curtain airbags as standard equipment suggests a broader shift toward baseline protection in segments historically treated as optional. This creates demand visibility and volume stability for suppliers that can meet durability, service, and fleet-level specification requirements. The opportunity is in scalable module architectures, simplified service interfaces, and fleet-oriented documentation and support. The risk is margin pressure if standardization triggers price competition without accompanying engineering or service differentiation.
Automotive Airbags Market
Trend Three: EV- and Platform-Specific Safety Architectures Drive Customization Demands
Electric vehicle platforms continue to alter interior packaging, weight distribution, and component placement, which in turn affects airbag deployment zones and module form factors. Suppliers that can adapt quickly to platform-specific constraints will capture premium positioning and repeat business across model cycles. The upside is a shift from commoditized replacement logic to engineered safety integration, where value is tied to packaging efficiency and validation speed. The uncertainty is platform volatility: rapid EV redesign cycles can compress supplier development windows and increase engineering cost if not managed with early engagement and flexible module strategies.
Across these trends, the consistent commercial thread is that airbag value will increasingly be defined by integration, application breadth, and responsiveness to vehicle architecture changes rather than by component volume alone. Organizations that treat safety systems as part of a broader vehicle architecture and mobility-solution context will be better positioned to convert growth into durable margin.
Actionable Implications for Decision-Makers
-
For manufacturers and suppliers: Prioritize integration across inflators, fabrics, and module engineering to reduce lead-time variability and improve cost control during material price swings. Invest in external-protection and specialty application capabilities where validation pathways are achievable and regional demand signals are strengthening. Build reverse-logistics and recall-readiness processes into the operating model to manage waste regulation exposure and maintain customer confidence during field actions.
-
For investors: Focus on suppliers with durable automaker relationships, multi-product restraint exposure, and the ability to extend safety technology into adjacent applications. Evaluate exposure to regulatory-driven standardization in commercial vehicles and to EV-specific packaging adaptation, as these can shape volume visibility and engineering intensity. Monitor concentration dynamics and regional compliance readiness, since ICTS-related rules and material sourcing constraints can influence margin stability and geographic mix.
-
For procurement teams and fleet operators: Treat safety specifications as strategic levers rather than fixed checkboxes. Standard packages can improve fleet safety profiles and reduce incident-related operational friction, but they should be weighed alongside service support, regional compliance alignment, and supplier capability to handle nonstandard configurations. Engage early with suppliers on EV and commercial-platform requirements to secure packaging feasibility and validation timelines before specification lock-in.
The strategic value of these decisions depends on the granularity of the underlying data. Regional revenue distribution, type-level growth differentials, application-specific penetration patterns, and competitive share movements can materially change sourcing, investment, and product-planning choices. Detailed segmentation, forward volume assumptions, and company-level positioning are most useful when aligned to specific vehicle programs, geographic commitments, and margin targets. For teams that require that level of precision, a full research report can provide the supporting breakdowns and scenario detail needed to translate these market-level insights into operational planning.
The airbag market is not simply growing; it is being redefined by broader protection concepts, standardization pressure in commercial segments, and platform-specific adaptation in electric vehicles. Participants that align engineering, compliance, and application strategy with these shifts will be better positioned to convert market expansion into sustained competitive advantage.
PW Consulting
For detailed analysis of this topic, please visit the official page: Airbag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wheat Seeds Market: Why the 3.75% CAGR and Asia Pacific Shift Changes Everything
By PW Consulting, 2026-09-21
Cultivating Growth: Strategic Trends and Commercial Opportunities in the Global Wheat Seeds Market
The global wheat seeds market is navigating a complex phase of structural transformation, balancing steady baseline expansion against breakthrough technological and regulatory shifts. Valued at approximately 5.4 billion USD in 2025, the sector has demonstrated consistent growth over the past half-decade, with revenue climbing from 4.52 billion USD in 2020 to the current level. Driven by a compound annual growth rate of 3.75 percent, the market is projected to approach 6.94 billion USD by 2032. This trajectory reflects more than population-driven demand; it captures an agricultural ecosystem under pressure to deliver higher yields, enhance climate resilience, and adapt to an increasingly fragmented regulatory and competitive environment. For stakeholders operating in or adjacent to wheat production, understanding where growth is structurally anchored—and where hidden inflection points lie—is essential for long-term positioning.
Beneath the aggregate growth figures, several structural realities define the competitive arena. The market is moderately consolidated but far from monopolistic, with the top three players commanding roughly 26.5 percent of revenue and the top five collectively holding 31.8 percent. This leaves considerable distributed capacity among regional specialists, niche breeders, and emerging biotechnological entrants. Meanwhile, the fundamental product architecture remains tilted toward established cultivation cycles, with winter wheat genetics accounting for the largest share of commercial activity, while spring and durum varieties serve distinct agronomic and milling requirements. The dominant use case remains commercial planting, which dwarfs smaller-scale and personal cultivation channels. The following analysis unpacks the forces reshaping this landscape, evaluates how incumbents and challengers are responding, and maps actionable pathways for executives, investors, and procurement leaders.
Market Snapshot and Core Challenges
A Steady Growth Curve Meets Structural Friction
The historical performance of the wheat seeds market from 2020 through 2025 illustrates resilience rather than volatility. Growth was neither explosive nor stagnant; instead, it reflected incremental adoption of improved genetics, steady acreage expansion in key growing zones, and gradual replacement cycles in established seed portfolios. The forecast period through 2032 projects continued expansion, though the pace suggests maturation rather than disruption in baseline demand. The real story lies not in headline numbers but in the pressure points emerging beneath them.
Hemp Seeds Market
Three interconnected challenges define the current inflection point. First, genetic yield plateaus in conventional breeding programs are forcing players to look beyond traditional trait stacking toward hybridization and gene-edited solutions, both of which carry higher development costs and longer commercialization timelines. Second, regulatory asymmetry across major growing regions is fragmenting what would otherwise be a more unified global rollout of advanced seed technologies, forcing companies to navigate divergent approval timelines, labeling requirements, and consumer acceptance thresholds. Third, supply chain volatility in parent seed production, propagation infrastructure, and input costs is compressing margins for mid-tier breeders while rewarding those with vertically integrated or regionally optimized distribution networks. These pressures do not halt growth, but they reshape who captures value and at what cost.
Where Pressure Turns Into Opportunity
The same constraints that challenge incumbents create entry points for organizations that can align innovation with regional readiness and risk mitigation. Hybridization, for instance, has historically struggled with wheat due to self-pollination biology and layout complexity, yet recent registration milestones and insurance provisions for parent seed production are lowering barriers to commercial scale. Similarly, the emergence of climate-resilient and input-efficient genetics is shifting procurement conversations from price-per-unit toward total agronomic value, allowing premium positioning where performance data and regulatory clarity align. Understanding which sub-segments are ready for technology adoption—and which remain dependent on cost-driven conventional offerings—is the first step in mapping a credible growth strategy.
Key Drivers Reshaping the Market
Technological Breakthroughs in Wheat Genetics
The most consequential shift in the wheat seeds market is the gradual translation of hybrid and biotechnological concepts into commercial reality. Wheat has long been considered a challenging crop for hybridization due to its floral structure and inbreeding tendencies, but targeted breeding platforms, doubled haploid techniques, and precision trait introgression have begun to overcome those biological constraints. Hybrid wheat varieties promise yield advantages, improved standability, and enhanced stress tolerance, yet they also require reliable parent seed supply chains and farmer confidence in replanting economics. The barrier to adoption is no longer purely biological; it is commercial infrastructure and trust in performance consistency.
Alongside hybridization, gene-editing and transgenic approaches are moving from pilot stages to limited commercial availability. The first commercial distribution of HB4 GM wheat seeds in Argentina marked a landmark shift, demonstrating that drought-tolerant and productivity-enhancing wheat traits can reach the market when regulatory pathways and regional acceptance align. This development does not instantly rewrite the global seed portfolio, but it establishes a reference point for what is technically possible and commercially viable under the right conditions. For breeders and technology platforms, the strategic implication is clear: incremental trait improvement is no longer sufficient where climate volatility and input constraints are accelerating. Differentiated performance under stress is becoming the core value proposition.
Policy and Regulatory Dynamics as Market Architects
Regulation continues to function as both a gateway and a competitive filter. Recent policy moves illustrate how regulatory clarity can unlock segments that were previously stalled by uncertainty. The introduction of hybrid wheat seed crop provisions for the 2026 crop year and beyond, including insurance coverage for parent seed production by seed companies, directly addresses a long-standing risk in hybrid wheat commercialization. By reducing the financial exposure associated with maintaining parent lines, such provisions lower the threshold for scaled deployment and encourage greater investment confidence from both seed developers and growers.
At the same time, merger activity and concentration trends in the broader seeds and agricultural chemicals sector remain under institutional scrutiny, with documentation pointing to the four largest firms holding a significant share of the global seed market. This concentration is not necessarily negative for innovation; in many cases, it provides the capital base required for long-cycle breeding programs and trait development. However, it also raises the stakes for regional players and specialty breeders, who must compete on localized adaptation, service intensity, and niche performance rather than scale alone. The regulatory environment is therefore shaping not just which technologies reach the field, but which organizational models can sustainably support them.
Demand-Side Shifts and the Total Value Conversation
On the demand side, wheat procurement is increasingly influenced by a wider set of criteria beyond yield per hectare. Farmers and agribusiness buyers are weighing stability under variable weather patterns, input efficiency, disease pressure management, and end-market quality requirements. Food processors, livestock operators, and export-oriented supply chains are pushing for consistency in protein content, milling characteristics, and agronomic predictability, which in turn shapes the seed selection logic at planting time. This broader value calculus supports premium offerings where performance can be demonstrated and documented, but it also raises the evidentiary burden for new genetics.
Consumer sentiment and export market standards add another layer of complexity. In regions where non-GM or conventionally bred wheat maintains stronger market acceptance, the route to advanced genetics may rely on gene editing or precision breeding rather than transgenic approaches, or it may focus on hybrid vigor without altering the crop's regulatory classification. In contrast, markets facing acute water stress or yield instability may show greater openness to drought-tolerant or stress-resilient seed technologies. This divergence means that demand growth is not uniform; it is conditional on regional risk profiles, end-use requirements, and the speed at which agronomic proof is translated into commercial trust.
Supply Chain and Cost Structure Pressures
The economics of seed multiplication remain a critical constraint. Parent seed production, purification, and distribution require reliable sourcing, biosecurity controls, and logistics that can preserve genetic integrity across batches. In a period of input cost variability and logistics disruption, the cost structure of seed supply can determine whether a promising variety reaches commercial scale or remains confined to limited trials. Companies with stronger regional multiplication capacity, tighter quality assurance, and better integration with agronomic service networks are better positioned to manage these pressures.
Cost pressures also influence portfolio decisions. High-development technologies must be matched with realistic commercialization pathways and pricing models that growers can absorb without sacrificing overall farm economics. This dynamic rewards strategies that combine clear performance differentiation with practical deployment support, including guidance on planting windows, crop management, and expected return under local conditions. Where seed suppliers can reduce uncertainty for the buyer, pricing becomes less of a standalone negotiation and more of a component in a broader agronomic partnership.
Competitive Landscape and Leading Strategies
Incumbents Anchored in Scale, Pipeline, and Regional Depth
The mature players in the wheat seeds market approach the sector from different angle points, but a common theme is the integration of breeding capability with broader crop portfolios and downstream support. Bayer AG continues to leverage its global reach and integrated crop science platform to offer wheat genetics alongside complementary crop protection and digital agronomy tools. Its differentiation rests on scale, multi-environment testing capacity, and the ability to bundle seed solutions with management practices that stabilize outcomes across variable conditions.
Corteva Agriscience brings a strong emphasis on trait development and corn-and-soy Adjacent technology platforms, while maintaining a focused wheat seed offering that benefits from rigorous breeding pipelines and farmer-facing service networks. Its strategic value lies in combining genetics with agronomic advisory capabilities and in leveraging data from broadacre cropping systems to improve selection accuracy and deployment timing.
Syngenta Group has moved aggressively to strengthen its hybrid wheat presence, most visibly with recent registration and launch activity around hybrid wheat varieties for European sowing seasons. By securing approvals and making specific hybrids available for upcoming planting cycles, Syngenta is attempting to convert technological readiness into commercial momentum. Its differentiation strategy emphasizes hybridization as a yield and resilience lever, backed by variety-specific availability and regional launch timing.
BASF SE has similarly positioned hybrid wheat seed sales as a contributing element within its agricultural solutions segment, with a particular focus on European markets for the 2025/2026 cycle. For BASF, the wheat seed opportunity is not isolated; it is part of a broader crop solutions ecosystem where seed, chemistry, and digital support can be aligned to improve field outcomes. This integrated posture helps justify investment in higher-complexity seed technologies by linking them to wider value capture.
Specialists, Regional Breeders, and the Distributed Edge
Beyond the largest multinationals, a substantial layer of specialized and regionally rooted companies competes on adaptation, responsiveness, and niche performance. Groupe Limagrain, KWS SAAT SE & Co. KGaA, RAGT Semences, and Florimond Desprez each bring deep European breeding traditions and strong local market knowledge, often with varieties tailored to specific soil, climate, and end-use conditions. Their strength is not necessarily to outspend global incumbents, but to offer varieties and service models that resonate with regional growers seeking locally validated performance.
In the Americas, companies such as AgReliant Genetics, Land O'Lakes Inc., ProHarvest Seeds, and AgriMAXX Wheat reflect different models of distribution, cooperative alignment, and wheat-focused breeding. AgReliant Genetics operates with a multi-channel seed business structure, while Land O'Lakes Inc. benefits from its broader agricultural cooperative network, which can support seed adoption through established customer relationships and region-specific agronomic support. ProHarvest Seeds and AgriMAXX Wheat illustrate how focused wheat portfolios can build loyalty by concentrating on core growing zones and practical farmer-facing value.
Bioceres Crop Solutions represents a distinct strategic profile, combining trait technology development with commercial execution in markets open to advanced wheat genetics. Its early commercial activity with HB4 GM wheat in Argentina underscores a strategy centered on regulatory-first market entry and targeted geographic deployment rather than global simultaneous rollout. This model highlights how technology differentiation can be paired with market selectivity to create early-mover advantage in specific jurisdictions.
How the Competitive Map Is Evolving
The current landscape is characterized by simultaneous consolidation pressure and differentiation opportunity. On one side, the largest firms continue to benefit from scale, capital intensity, and cross-portfolio synergies, which supports long-cycle breeding investment and global testing networks. On the other side, the distributed base of regional breeders and specialty players retains relevance by offering locally adapted genetics, flexible supply relationships, and stronger direct engagement with growers. The market has not tipped toward a single formula; rather, it is bifurcating into scale-driven technology platforms and regionally optimized performance specialists.
Rice Seed Market
New entry and expansion are most likely where technological readiness converges with regulatory clarity and where supply chain readiness supports multiplication at commercial scale. Hybrid wheat is a prime example: the biological and operational challenges are being reduced by improved breeding methods and supportive risk provisions, but commercial success still depends on regional launch timing, parent seed availability, and farmer adoption economics. Biotechnology-driven wheat traits face an even more selective path, with early progress tied to specific regulatory environments and end-market acceptance. In both cases, the winners are likely to be organizations that can synchronize technology, geography, and commercial infrastructure instead of treating each as an independent variable.
PW Consulting Health Care Research Center
Future Trends and Strategic Opportunities (2026-2032)
Hybridization Moves From Demonstration to Commercial Scale
Hybrid wheat is expected to transition from a promising concept to a more mainstream commercial category over the next several years, particularly in regions where registration pathways are navigable and parent seed production can be supported with manageable risk. The combination of improved breeding platforms, targeted launch strategies, and policy provisions that reduce production risk creates a more favorable environment for scaled deployment. The commercial opportunity lies not simply in selling a different seed category, but in building the accompanying agronomic support, quality assurance, and supply reliability that make hybrid adoption economically rational for growers. Companies that can prove consistent performance, manage multiplication risk, and deliver clear return expectations will be best positioned to capture share in this transitioning segment.
Regional Differentiation as the New Competitive Default
As technology portfolios become more diverse, regional differentiation will increasingly define competitive success. Uniform global rollouts will remain limited by divergent regulatory acceptance, varying climate stress profiles, and different end-use quality requirements. The strategic implication is that seed innovation will be adopted unevenly, with some regions prioritizing hybrid vigor, others focusing on drought or heat tolerance, and still others emphasizing disease resistance or milling quality. This unevenness creates space for organizations that build region-specific evidence packages, align variety selection with local risk profiles, and tailor service models to regional procurement behavior. Growth will increasingly come from matching the right technology to the right conditions, not from pushing a single offering everywhere.
Ecosystem Integration and Data-Enabled Deployment
The third trend is the deepening integration of seed offerings with broader crop management ecosystems. Advanced seed technologies are more valuable when paired with practical guidance on planting windows, nutrient management, pest pressure timing, and harvest strategy. This creates an opportunity for seed providers to strengthen their role as agronomic partners rather than product vendors alone. Data from multi-environment trials, on-farm performance monitoring, and localized management recommendations can improve adoption confidence and support premium positioning where results are repeatable. At the same time, the trend raises the bar for operational excellence: the organizations that win will be those capable of linking genetic potential with field-level execution in a consistent, credible way.
Potential Risks and Unresolved Uncertainties
Despite a constructive growth outlook, several uncertainties warrant caution. Regulatory divergence may slow or fragment the rollout of advanced wheat technologies in key export and consumption markets, limiting the addressable opportunity for certain trait types. Adoption risk remains significant for hybrid wheat if parent seed supply, seed pricing, or replanting economics fail to meet grower expectations. Concentration dynamics may also create pressure on smaller breeders, especially where scale advantages in testing, multiplication, and distribution become harder to offset. Finally, climate volatility can produce localized mismatches between variety performance assumptions and actual field conditions, underscoring the need for robust testing, transparent communication, and flexible portfolio management.
Strategic Recommendations for Decision-Makers
For Seed Manufacturers and Trait Developers
Prioritize commercialization pathways that align technology readiness with regional regulatory clarity and multiplication capacity. Where hybrid wheat or advanced trait offerings are being prepared, build the supply chain and agronomic support infrastructure in parallel rather than treating them as afterthoughts. Focus on varieties and traits that deliver measurable performance under local stress conditions, and document results in a way that reduces buyer uncertainty. Differentiation will increasingly depend on how convincingly a company can connect genetics to field-level outcomes, not just on breeding novelty alone.
For Investors and Strategic Backers
Evaluate opportunities through the lens of regional readiness and execution capability rather than technology promise alone. The most attractive risk-adjusted bets are likely to sit at the intersection of clear regulatory standing, credible parent seed or multiplication logistics, and strong local distribution or service relationships. Monitor concentration trends, but also watch for regional specialists and biotechnology-first entrants that can establish early dominance in receptive markets. In wheat, the path to value creation is often incremental and geography-specific, which means due diligence should emphasize deployment feasibility as much as scientific differentiation.
For Procurement Leaders and Grower-Serving Organizations
Shift seed purchasing conversations from unit price toward total agronomic risk reduction and performance stability. Where advanced genetics are available, test them against local conditions and evaluate the full support package, including planting guidance, multiplication reliability, and expected performance consistency across variable seasons. Diversifying portfolios by matching varieties to specific risk profiles and end-use requirements can improve resilience without relying on a single flagship offering. In practice, the strongest procurement strategies will combine selective adoption of differentiated seed technologies with disciplined evaluation of supply reliability and local agronomic fit.
Closing Perspective
The wheat seeds market is not on the verge of a single disruptive shift; it is undergoing a series of reinforcing changes that reward organizations capable of integrating technology, geography, and execution. Steady baseline growth provides a durable foundation, while hybridization, regulatory developments, demand-side value recalibration, and supply chain dynamics are reshaping where additional value is created. The competitive map remains layered, with global scale players, regional specialists, and technology-first entrants each pursuing distinct routes to advantage. For executives, investors, and procurement leaders, the strategic task is to identify which sub-segments, geographies, and technology pathways align with operational capabilities and risk tolerance. Detailed segmentation data, company-level comparisons, and customized strategic scenarios can sharpen that assessment further and support more confident decisions in a market where timing and fit increasingly determine outcomes.
For detailed analysis of this topic, please visit the official page: Wheat Seeds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ceramic Ink Market: How 5.79% CAGR and Asia Pacific Demand Reshape Growth
By PW Consulting, 2026-09-21
Navigating the Ceramic Ink Market: Strategic Trends and Commercial Opportunities Through 2032
The global ceramic ink market has entered a phase of steady, technology-driven expansion. Valued at approximately 2.71 billion USD in 2020, the segment climbed to 3.59 billion USD by 2025, and forward projections indicate a trajectory toward 5.32 billion USD by 2032. This growth reflects a compound annual rate of 5.79 percent across the forecast horizon. While the absolute numbers signal a mature, resilient market, the underlying composition tells a more nuanced story. Regional demand is increasingly concentrated in high-volume manufacturing corridors, functional formulations are outpacing decorative variants in both volume and margin potential, and ceramic tile applications continue to dominate downstream consumption. For decision-makers, the headline growth rate matters less than the structural shifts that will determine which players capture disproportionate value in the next cycle.
Worldwide Specialty Ink Market
The market is not expanding uniformly. Growth is being pulled forward by regions with heavy ceramic production footprints, while mature markets are shifting from volume-driven expansion toward premiumization and regulatory compliance. Functional inks, which enable advanced surface properties beyond aesthetics, now represent the larger revenue share and are expected to retain their lead as technical specifications tighten across construction, packaging, and consumer goods verticals. Decorative inks remain critical for design differentiation, but their growth trajectory is increasingly tied to digital printing adoption rather than traditional manual or mechanical decoration methods. On the application side, ceramic tiles account for the largest consumption base, followed by glass printing and food container printing. Each vertical carries distinct performance requirements, regulatory exposures, and cost sensitivities, which means aggregated market figures can obscure pockets of volatility and opportunity.
Structural Headwinds and Inflection Points
Despite the positive top-line outlook, the industry faces a narrow set of challenges that will shape competitive positioning over the coming years. First, environmental and emissions regulations are tightening across key export and domestic markets, particularly in Europe and increasingly in Southeast Asia. Manufacturers are being asked to deliver formulations that maintain performance while reducing volatile organic compounds, odor, and hazardous substances. This is not a compliance checkbox; it is a reformulation burden that affects raw material sourcing, process control, and validation cycles. Companies that treat sustainability as an afterthought will face margin compression and delayed time-to-market, while those that design low-emission architectures early can convert regulatory pressure into a defensible product advantage.
Second, the technical bar for ink performance is rising as digital decoration systems become more capable and more widely deployed. Inorganic pigment-based ceramic inks must withstand fine milling, precise dispersion, and high-temperature firing conditions that can exceed 1250 degrees Celsius in tile production. This requires tighter supplier coordination, consistent batch quality, and formulation stability across varying line speeds and substrate types. As digital printing moves from pilot lines to high-throughput production environments, even minor inconsistencies in viscosity, particle size distribution, or adhesion can translate into elevated rejection rates and operational downtime. The inflection point here is clear: ink is no longer a commoditized consumable but a critical process enabler whose performance directly affects overall equipment effectiveness.
Third, supply chain localization is becoming a strategic necessity rather than a logistical preference. Ceramic manufacturing clusters in Southeast Asia, particularly in Vietnam and Indonesia, are expanding capacity and attracting both machinery and ink suppliers seeking closer proximity to end users. At the same time, procurement teams are increasingly sensitive to lead times, freight volatility, and currency exposure. The result is a market where regional responsiveness, localized technical support, and flexible inventory models are gaining importance alongside product performance. Organizations that remain dependent on distant, inflexible supply structures risk slower reaction times and weaker customer intimacy in fast-moving production markets.
Key Drivers Shaping the Next Growth Cycle
Technology Innovation and Formulation Breakthroughs
Technology is the most visible driver of market evolution, and its influence is accelerating across both product design and production integration. The shift toward low-emission digital inks is a case in point. Recent product announcements highlight formulations that reduce harmful emissions and volatile organic compounds by up to 50 percent compared with standard eco-inks, while also introducing almost no-smelling components to lower environmental impact in factory environments. These advances are not merely cosmetic improvements; they reflect a broader engineering push to reconcile high-temperature durability with workplace safety and regulatory expectations. For manufacturers, this means ink selection increasingly involves trade-offs between adhesion, color consistency, firing tolerance, and emissions profile, all of which must be validated on specific production lines.
Ceramic Package Market
At the same time, inorganic pigment-based ceramic inks continue to demand sophisticated milling and dispersion processes to remain compatible with extreme firing conditions. This technical complexity creates a barrier to entry that favors incumbents with deep formulation expertise and testing infrastructure. It also raises the value of application engineering, because the same ink can behave differently depending on printhead configuration, substrate preparation, and kiln parameters. The commercial implication is that differentiation is moving upstream into R&D capability, quality control rigor, and customer-facing technical support. Companies that can demonstrate repeatable performance across diverse digital decoration setups are better positioned to command premium pricing and longer contract tenure.
Policy and Regulatory Environment
Regulatory dynamics are acting as both a constraint and a catalyst. European REACH compliance and broader environmental impact reduction goals are pushing ink suppliers to redesign formulations and document material safety more comprehensively. This has already prompted notable product launches focused on low-VOC architectures, signaling that compliance is becoming a product development priority rather than a reactive adjustment. In parallel, regional manufacturing expansion in Southeast Asia is shaping a new regulatory landscape where local content expectations, environmental standards, and export requirements intersect. Ink producers and distributors that proactively align their portfolios with these evolving standards can reduce the risk of market access delays and position themselves as preferred partners for manufacturers seeking globally acceptable output.
The regulatory dimension also affects downstream demand. Tile manufacturers and homeware producers facing stricter emissions criteria in their own operations are increasingly inclined to select inks that simplify their compliance burden. This creates a pull effect where ink specifications are evaluated not only on print quality but also on the broader environmental footprint of the decorated product. As a result, regulatory alignment is becoming a commercial differentiator, especially in markets where export competitiveness depends on meeting diverse destination-country requirements.
Demand-Side Shifts in Consumer and Industrial Behavior
Demand is being reshaped by the broader adoption of digital decoration in high-volume ceramic production. In markets with massive tile output, digital ink adoption is accelerating as producers seek greater design flexibility, shorter changeover times, and more consistent repeatability across batches. This shift is not limited to luxury or custom segments; it is increasingly relevant in standard production lines where manufacturers want to respond faster to fashion cycles and regional preference variations without sacrificing throughput. The net effect is a rising appetite for ink systems that can support frequent design changes while maintaining line stability.
On the decorative side, consumer expectations continue to push for richer patterns, more realistic textures, and tighter color matching across product families. These expectations place additional pressure on ink color fidelity and gloss control. Meanwhile, functional requirements are expanding beyond aesthetics into areas such as surface durability, hygiene compatibility, and specialized coatings for containers and glass applications. The demand story is therefore bifurcating: volume-driven tile markets want reliability and speed, while design-sensitive and functional applications want performance precision. Ink manufacturers that can serve both poles with a coherent portfolio and clear application guidance are likely to capture a broader share of wallet.
Supply Chain and Cost Structure Dynamics
Cost structures are evolving as raw material inputs, energy considerations, and logistics complexity interact with formulation intensity. Inorganic pigment-based inks require fine milling and dispersion, which means that processing quality and material consistency have direct implications for yield and cost per fired unit. Any disruption in pigment supply, solvent availability, or specialized additives can ripple through the value chain and affect both pricing and delivery reliability. At the same time, the trend toward localized production in Southeast Asia is altering the cost calculus by reducing transport distances for certain markets while introducing new operational requirements around regional quality assurance and technical staffing.
This shifting cost environment rewards suppliers that can balance formulation sophistication with manufacturing efficiency. It also rewards buyers who evaluate total cost of ownership rather than unit price alone. In practice, that means factoring in waste reduction, printhead compatibility, cleaning frequency, firing stability, and rework rates. Ink that appears cheaper on a per-liter basis may underperform when measured against line efficiency and finished-product quality. As procurement teams become more sophisticated in this assessment, suppliers with transparent performance data and strong application support gain an advantage in price negotiations.
Competitive Landscape and Leading Strategies
Incumbents with Technical Depth and Regional Reach
The market features a mix of specialized ink manufacturers, global equipment-linked ink providers, and ceramic machinery groups that also supply inks and glazes. Sicer S.p.A. stands out for its focus on digital inks tailored to ceramic tile decoration, including low-emission formulations and custom series designed for specific decoration workflows. Its recent emphasis on low-emission digital inks achieving up to 50 percent VOC reduction illustrates how a focused manufacturer can turn environmental pressure into a product story. A.T. Inks, based in India, positions itself as a large-scale producer of inorganic pigment-based ceramic inkjet inks for wet-on-wet tile printing up to 1250 degrees Celsius firing. Its scale and formulation orientation make it relevant for high-volume producers seeking reliable pigment performance under extreme firing conditions.
NUtec Digital Ink operates with a broader digital ink portfolio spanning UV-cured, solvent, and water-based systems, supporting ceramic printing and homeware applications. This multi-technology footprint allows it to serve customers with varied process preferences and substrate requirements. EFI brings long-standing formulation expertise in eco-solvent and water-based ceramic inks for digital tile decoration, which positions it as a partner for producers already embedded in its equipment ecosystem or seeking proven compatibility. KEDA Industrial Group, as a ceramic machinery supplier, showcases inks and glazes alongside equipment at industry events, reinforcing an integrated value proposition that appeals to manufacturers looking to streamline supplier relationships and align ink selection with machine capability.
Strategic Positioning and Differentiation
Across these players, differentiation is emerging along three axes: formulation specialization, regulatory readiness, and application ecosystem support. Formulation specialization matters because high-temperature durability, color consistency, and printhead compatibility are not trivial to achieve at scale. Regulatory readiness matters because low-emission and low-VOC positioning is increasingly tied to market access and customer procurement criteria. Application ecosystem support matters because digital decoration success depends on more than the ink bottle; it depends on line integration, maintenance practices, and troubleshooting responsiveness. Suppliers that combine these elements can move beyond transactional selling and into solution-level relationships.
Recent industry developments reinforce this direction. The launch of new low-VOC ceramic ink lines to reduce environmental impact demonstrates a clear regulatory and sustainability response. The opening of new manufacturing facilities in Vietnam for Southeast Asia operations reflects the localization theme and the desire to serve emerging ceramic clusters with shorter supply chains. Trade show participation and product announcements continue to be important signaling mechanisms, particularly in regions where face-to-face technical engagement and live demonstrations influence procurement decisions. Taken together, these moves indicate that competitive advantage is being built through a combination of product engineering, geographic responsiveness, and visible commitment to compliance and customer support.
Evolution of the Market Structure
The market is not heading toward a simple monopoly or a fragmented free-for-all. It is more likely to evolve through selective consolidation among suppliers seeking broader portfolios and geographic coverage, alongside continued specialization by niche players who serve specific printing technologies, verticals, or regional needs. New entrants may appear, but the technical barriers around high-temperature performance, dispersion quality, and application validation will remain significant. As a result, the most disruptive threats may not come from isolated ink startups but from integrated equipment-ink-material combinations that simplify adoption for tile manufacturers and homeware producers. The competitive logic is shifting from product-only competition to process-level relevance, where ink is evaluated as part of a larger digital decoration system.
Forecasting the Next 3–5 Years
Trend 1: Low-Emission and Compliant Formulations Will Become Baseline Expectations
Over the next few years, low-emission and low-VOC architectures will transition from premium differentiators to baseline requirements in many markets. This shift will be driven by regulatory momentum, workplace safety expectations, and downstream customer preferences for cleaner production processes. Ink suppliers that treat this as a one-time reformulation exercise may find themselves repeatedly catching up, while those that build compliance and emissions reduction into their core formulation philosophy can offer a more stable value proposition. The commercial opportunity lies in packaging compliance with performance, so that customers do not have to choose between environmental goals and print quality.
PW Consulting
Trend 2: Digital Integration Will Deepen the Value Chain
Digital decoration will continue to expand beyond high-end segments into broader production volumes, especially in regions with large-scale ceramic output. As this happens, ink will become more tightly coupled with printer configuration, substrate preparation, and firing profiles. The result will be greater demand for integrated solutions, technical validation services, and application-specific tuning. This trend favors suppliers that can support line trials, provide repeatable setting parameters, and help customers reduce trial-and-error cycles. It also raises the stakes for equipment-ink compatibility, which may encourage closer cooperation between ink manufacturers and printer makers.
Trend 3: Regional Manufacturing Hubs Will Reshape Supply and Demand Patterns
Southeast Asia’s ceramic manufacturing clusters will continue to influence where ink capacity is located, how quickly new products reach end users, and how suppliers compete on responsiveness. Localized production and support can shorten feedback loops, improve service levels, and reduce exposure to long-haul logistics disruptions. At the same time, regional expansion introduces challenges around quality consistency, talent development, and coordination across multiple markets with different regulatory and customer expectations. The strategic opportunity is to build regional presence that is not merely logistical but technically credible, with local teams capable of supporting formulation queries, line optimization, and compliance documentation.
Associated Risks and Uncertainties
These trends carry meaningful uncertainties. Regulatory requirements may diverge across regions, creating compliance complexity for globally distributed portfolios. Raw material availability and energy cost fluctuations can pressure margins, especially for formulations that depend on specialized pigments and dispersion processes. Demand may also shift faster than expected if digital adoption accelerates in some markets while lagging in others, leaving suppliers with uneven capacity utilization. Finally, competition from integrated equipment-ink offerings could compress standalone ink pricing in certain segments, particularly where customers prioritize convenience and system compatibility over independent supplier choice. Companies that monitor these signals closely and maintain flexible product and supply strategies will be better positioned to adapt.
Actionable Recommendations for Decision-Makers
For Manufacturers and Production Leaders
Evaluate ink selection as a process decision rather than a consumable purchase. Prioritize trial data that reflects your actual line speeds, substrates, and firing conditions, and compare total cost of ownership across performance, waste, rework, and maintenance. If environmental compliance is becoming more important to your customers or your own operations, ask suppliers for clear documentation on emissions profiles, material safety, and validation support. Where digital decoration is expanding, invest in application engineering relationships that can help stabilize settings and reduce changeover friction. A disciplined evaluation framework will help avoid false economies from low-cost inks that underperform in production.
For Investors and Strategy Teams
Look for value creation at the intersection of formulation strength, regulatory readiness, and regional service capability. Companies that can demonstrate low-emission performance without sacrificing firing durability, and that maintain credible technical support in growth markets, are likely to earn stronger customer loyalty and more defensible margins. Pay attention to integration signals as well: partnerships or product alignments between ink suppliers and equipment providers may reveal where the market is heading in terms of bundled solutions and channel power. In parallel, track capacity expansion in Southeast Asia and the associated localization of supply chains, since these moves can influence both competitive intensity and regional demand trajectories.
For Procurement and Sourcing Professionals
Broaden evaluation criteria beyond unit price to include consistency, compatibility, and compliance readiness. Request performance evidence tied to high-temperature firing and digital print workflows, and verify that suppliers can support repeat orders with stable specifications. Consider multi-supplier or region-specific sourcing strategies if your production footprint spans multiple markets with different regulatory or logistics conditions. Where possible, negotiate for clear application support and issue resolution timelines, since responsiveness during line problems often matters more than marginal price differences. A well-structured sourcing approach can reduce operational risk while preserving flexibility as production needs evolve.
The ceramic ink market is moving through a period where growth is real but uneven, and where competitive advantage depends on how well companies align product performance with regulatory expectations, digital production realities, and regional demand patterns. The organizations that will benefit most are those that treat ink as a strategic input, build evidence-based procurement and investment decisions, and stay attentive to the intersection of formulation science, compliance, and market localization. For leaders who need a more granular view of segment dynamics, regional breakdowns, application-level demand splits, and company-level positioning beyond the trends outlined here, the full research report provides the detailed segmentation data and customized analysis required to translate these insights into concrete plans.
For detailed analysis of this topic, please visit the official page: Ceramic Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Licorice Extract Market: Inside the 5.4% CAGR and 300.6M USD Revenue Shift
By PW Consulting, 2026-09-21
The Licorice Extract Market: Navigating Strategic Shifts and Commercial Opportunities Through 2032
The global licorice extract market is experiencing a period of measured but steady expansion, driven by evolving consumer preferences, stringent regulatory frameworks, and technological advancements in extraction and formulation processes. Valued at approximately $208.2 million in 2025, the market has demonstrated consistent growth from its 2020 baseline of $160.5 million, with a projected expansion to $300.6 million by 2032. This trajectory reflects a compound annual growth rate of 5.4 percent across the forecast horizon, signaling a mature yet dynamic industry landscape. For executives, investors, and procurement leaders, understanding the underlying forces shaping this market is essential to capturing value while mitigating emerging risks.
Behind the headline figures lies a complex ecosystem where raw material volatility, regulatory divergence, and competitive differentiation converge. The market has already begun consolidating around a handful of established players, with the top three firms accounting for roughly 45 percent of global revenue and the top five commanding 65 percent. This concentration underscores the importance of strategic positioning, supply chain resilience, and regulatory agility. As the industry moves through the 2026–2032 forecast period, the convergence of technological innovation, shifting demand patterns, and policy evolution will reshape how value is created and captured across the licorice extract value chain.
Market Structure and Baseline Dynamics
The licorice extract market operates across multiple product formats, including powder, block, paste, and liquid, each serving distinct industrial and consumer applications. Powder remains the dominant format, reflecting its versatility in confectionery, pharmaceutical formulations, and nutraceutical blends. Block and paste formats cater to specialized processing needs, particularly in traditional food manufacturing and large-scale industrial applications, while liquid extracts are gaining traction in pharmaceutical and healthcare segments where rapid solubility and standardized dosing are critical.
Geographically, the market exhibits a multi-polar distribution, with significant volumes flowing through established production hubs and consumption centers. The interplay between regional sourcing availability, import dependency, and localized regulatory requirements creates a complex operating environment. Global trade in licorice extract reached approximately $156 million in 2024, reflecting a modest increase from the prior year and highlighting the market's reliance on cross-border supply chains. This trade dynamic is particularly pronounced in regions where domestic cultivation cannot meet industrial demand, forcing manufacturers and buyers to navigate currency fluctuations, freight costs, and geopolitical trade considerations.
Key Challenges and Inflection Points
Despite the favorable growth trajectory, the licorice extract market faces several structural challenges that will test operational resilience and strategic agility. Raw material price volatility stands out as a primary concern. Import prices for licorice root from major sourcing regions reached approximately $24.45 per kilogram in 2025, with significant fluctuations driven by weather patterns, harvest cycles, and shifting agricultural policies. This volatility directly influences extract production costs, compressing margins for manufacturers who cannot pass through price adjustments quickly or who lack long-term supply agreements.
PW Consulting
Regulatory complexity presents a second major challenge. In the United States, licorice is listed under 21 CFR 184.1408 with FEMA No. 2630, providing a clear pathway for use as a flavoring agent or adjuvant in food and beverage applications. Meanwhile, the European Union enforces mandatory labeling requirements for confectionery and beverages containing glycyrrhizinic acid or ammonium salt at thresholds of 100 mg/kg or 10 mg/L and above, with additional warnings for consumers with hypertension. These divergent frameworks create compliance overhead for multinational manufacturers and require careful formulation adjustments to meet region-specific thresholds. Glycyrrhizin content restrictions further limit food-grade formulations, with caps typically set between 50 and 100 ppm in finished products depending on the regulatory jurisdiction.
A third inflection point lies in the tension between traditional applications and emerging functional uses. While confectionery and tobacco remain steady demand anchors, the market is increasingly exposed to innovation-driven segments such as functional foods, cosmetics, and dietary supplements. Companies that fail to adapt their product portfolios to these shifting demand signals risk ceding share to more agile competitors or facing margin erosion as commodity-grade commoditization pressures intensify.
Key Drivers of Market Transformation
Technological Innovation and Extraction Advances
Technological progress in extraction methodologies and formulation science is reshaping the licorice extract market by enabling higher purity, consistent potency, and tailored functional profiles. Traditional water and solvent extraction methods are being augmented by optimized processing techniques that improve yield, reduce waste, and standardize glycyrrhizin and flavonoids content across batches. These advancements are particularly valuable for pharmaceutical and nutraceutical applications, where batch-to-batch consistency and documented active compound profiles are non-negotiable.
A notable example of innovation-driven differentiation emerged in April 2026, when Rohto Pharmaceutical Co., Ltd. launched a proprietary licorice extract powder containing Gliasperin B, recognized as Japan's first approved functional food ingredient for managing body fat. This launch illustrates how targeted research into bioactive compounds can unlock new application pathways and command premium positioning. Similarly, Norevo GmbH's January 2026 product catalog release emphasized confectionery applications across granules, powder, low-dust powder, paste, and block formats, signaling a strategic focus on format diversification to meet varied manufacturing requirements.
For industry participants, the implication is clear: extraction and formulation capabilities are no longer purely operational concerns but strategic differentiators. Companies that invest in process optimization, analytical quality control, and application-specific customization will be better positioned to serve high-value segments and defend against price-based competition.
Regulatory and Policy Environment
The regulatory landscape continues to exert a profound influence on market structure, product design, and go-to-market strategies. Clear regulatory classification in major markets provides stability for food and beverage applications, but the patchwork of regional requirements creates complexity for global suppliers. The U.S. framework, which recognizes licorice as a flavoring agent or adjuvant, offers a relatively straightforward compliance pathway for domestic manufacturers and importers. In contrast, EU labeling and warning requirements demand proactive formulation management and consumer communication strategies, particularly for products targeting health-conscious or medically sensitive demographics.
Glycyrrhizin content restrictions add another layer of strategic consideration. Caps at 50 to 100 ppm in finished food-grade products require manufacturers to balance potency, taste profile, and regulatory compliance. This dynamic favors suppliers that can offer standardized, certified extracts with verified glycyrrhizin levels, as well as those capable of blending or modifying formulations to meet specific market thresholds. For buyers, regulatory clarity reduces sourcing uncertainty, but it also raises the bar for supplier qualification and documentation.
The policy environment is likely to remain a stabilizing force for established applications while creating both barriers and opportunities for novel uses. Companies that maintain robust regulatory monitoring capabilities and engage proactively with compliance frameworks will gain a competitive edge in navigating regional differences and emerging requirements.
Demand-Side Shifts in Consumer and Enterprise Behavior
Consumer preferences and enterprise procurement patterns are evolving in ways that directly impact licorice extract demand. In the food and beverage sector, the continued popularity of licorice-flavored confectionery and traditional formulations provides a stable base, but growth is increasingly tied to clean-label positioning, natural ingredient sourcing, and functional claims. Manufacturers are responding by emphasizing natural extraction processes, traceable sourcing, and transparent ingredient documentation to align with consumer expectations.
In the pharmaceutical and healthcare segments, demand is driven by standardized extract requirements, evidence-based applications, and integration into broader wellness and therapeutic portfolios. The nutraceutical and dietary supplement space is seeing expanded interest in botanical ingredients with documented bioactive properties, creating opportunities for licorice extract providers that can support claims with robust quality assurance and application expertise. Cosmetics and personal care represent a smaller but growing niche, where licorice-derived compounds are valued for specific formulation properties and skin-care benefits.
Enterprise buyers are increasingly prioritizing supply reliability, documentation quality, and formulation support over pure cost minimization. This shift rewards suppliers that can offer technical assistance, regulatory documentation, and consistent supply performance. For procurement leaders, the trend underscores the importance of vendor evaluation criteria that extend beyond unit price to include compliance capability, innovation potential, and long-term supply security.
Supply Chain and Cost Structure Dynamics
Supply chain resilience has become a strategic imperative as raw material volatility and trade dynamics continue to influence cost structures. The reliance on imported licorice root in key markets means that production costs are sensitive to agricultural output, freight conditions, and currency movements. Import price fluctuations in 2025 highlighted the need for diversified sourcing strategies, forward contracting, and inventory management practices that buffer against short-term shocks.
Manufacturers are responding by strengthening relationships with multiple origin sources, investing in quality verification processes, and exploring vertical integration or long-term supply agreements where feasible. Geographic diversification of sourcing and production capacity can reduce exposure to region-specific disruptions and provide negotiating leverage in volatile markets. For downstream buyers, understanding supplier sourcing strategies and risk management practices is increasingly important when evaluating supply partners.
The cost structure dynamic also favors scale and operational efficiency. Companies with established extraction infrastructure, optimized logistics, and rigorous quality control can absorb input cost fluctuations more effectively than smaller or less integrated operators. This reality is contributing to the ongoing concentration trend, as larger players leverage their operational capabilities to maintain margins and invest in product development.
Competitive Landscape and Leading Strategies
The licorice extract market features a diverse set of global and regional players, each pursuing distinct strategic positioning based on geographic presence, application focus, and product format capabilities. Norevo GmbH, headquartered in Germany, has built a reputation around refined licorice extract offerings in powder, granules, paste, and block formats, with a particular emphasis on confectionery and food applications. The company's January 2026 catalog release underscores a strategy centered on format flexibility and application-specific solutions for food manufacturers.
MAFCO Worldwide LLC, based in the United States, positions itself as a global leader supplying pure derivatives and extracts of Glycyrrhiza species for food, beverage, and personal care sectors. Its broad application coverage and focus on purity and consistency align with the needs of large-scale industrial buyers seeking reliable, multi-application supply partners. F&C Licorice Ltd., operating from Israel, is recognized as one of the world's leading producers of licorice extract in powder, paste, and block forms, serving tobacco, confectionery, and pharmaceutical industries. This multi-industry footprint provides diversification and reduces dependence on any single application cycle.
Zagros Licorice Co. in Iran and Sepidan Osareh Co. also operate from key sourcing regions, focusing on licorice extract powder and derivatives for food, cosmetics, and herbal applications. Their geographic positioning provides proximity to raw material origins, which can translate into cost advantages and supply responsiveness, though they must also navigate trade and regulatory considerations in export markets. Ransom Naturals Ltd. in the United Kingdom specializes in liquid extracts for pharmaceutical, healthcare, and food and beverage sectors, emphasizing a format and application focus that differentiates it from powder- and block-oriented competitors.
In Asia, Shaanxi Jiahe Phytochemical Co. Ltd. in China and Aushadhi Herbal in India manufacture and export licorice extract as a key herbal ingredient for food, supplements, and pharmaceuticals. Their capabilities align with the growing demand for botanical ingredients in nutraceutical and pharmaceutical applications, and their export orientation positions them to serve international buyers seeking cost-competitive sourcing options. VPL Chemicals in India complements this landscape as a supplier of licorice extract and derivatives for food and pharmaceutical applications, adding further regional capacity and optionality for buyers.
Japanese firms Maruzen Pharmaceuticals Co., Ltd. and Rohto Pharmaceutical Co., Ltd. illustrate a different strategic orientation, focusing on proprietary extraction and formulation capabilities for cosmetics, food, and functional applications. Maruzen's development of polyol-soluble forms and glabridin for cosmetics and food applications highlights innovation in specialized compound extraction. Rohto's April 2026 launch of Lyconin®, a proprietary licorice extract powder recognized for body fat management, demonstrates how functional differentiation and regulatory approval can create premium positioning in the nutraceutical space.
Strategic Positioning and Differentiation Factors
Across this competitive set, several differentiation factors emerge. Format versatility allows suppliers to serve multiple processing requirements and reduce customer switching costs. Application breadth provides revenue diversification and cross-segment learning opportunities. Proprietary extraction or formulation capabilities enable premium positioning and functional claim support. Geographic proximity to raw material sources can improve cost structure and supply responsiveness, while strong regulatory documentation and quality systems build buyer confidence in highly regulated segments.
Leadership in the market is increasingly defined not just by volume output but by the ability to combine reliable supply, format flexibility, application expertise, and regulatory compliance. Companies that can offer end-to-end support—from sourcing transparency to formulation guidance—are better positioned to retain and expand relationships with demanding buyers.
Worldwide Picrorhiza Extract Market
Evolution of the Market Structure
The market structure is evolving along a trajectory of moderate consolidation among established players, coupled with continued entry of specialized or regionally focused suppliers. The concentration levels observed in the market reflect the advantages of scale, operational maturity, and multi-application portfolios. At the same time, demand for specialized formats, functional ingredients, and region-specific compliance support creates space for focused competitors that can serve niche requirements effectively.
Trade dynamics are also shaping competitive outcomes. Global trade in licorice extract has grown modestly, driven by import dependency in key consumption markets. This dynamic rewards suppliers with strong export capabilities, reliable logistics, and documentation competence. For buyers, the trade environment encourages a balanced sourcing strategy that combines cost competitiveness with supply security and regulatory alignment.
Over the forecast period, the market is likely to see further differentiation between commodity-oriented suppliers and those pursuing value-added positioning through innovation, certification, and application support. Mergers, partnerships, or capacity expansions may accelerate consolidation in certain regions, while new entrants could emerge in segments where functional or cosmetic applications create fresh demand vectors.
Future Trends and Commercial Opportunities Through 2032
Trend One: Functional and Wellness-Driven Applications Will Gain Share
The licorice extract market is poised to see incremental but meaningful growth in functional and wellness-oriented applications. The April 2026 launch of a licorice extract powder recognized for body fat management illustrates the potential for bioactive-focused formulations to enter regulated functional food channels. As consumer interest in natural ingredients with documented benefits continues to rise, suppliers that can provide standardized extracts, application guidance, and regulatory support will find expanding opportunities in nutraceuticals, functional foods, and select cosmetic applications.
For commercial strategy, this trend suggests a shift toward value-added positioning. Manufacturers and investors should evaluate capabilities in compound identification, standardization, and claim support as potential sources of differentiation. Procurement teams should assess supplier competence in functional application documentation and regulatory alignment when evaluating partners for wellness-oriented products.
Trend Two: Regulatory Harmonization Pressures Will Drive Standardization and Documentation Excellence
The divergence between regional regulatory frameworks will continue to shape product design and market access strategies. While full harmonization remains unlikely in the near term, the practical effect will be a growing premium on standardization, transparent documentation, and proactive compliance management. Suppliers that can deliver verified glycyrrhizin levels, clear labeling support, and region-specific formulation guidance will reduce friction for multinational buyers and strengthen their competitive position.
This trend also creates risk for operators that lack robust quality systems or regulatory monitoring capabilities. As labeling and content restrictions become more enforced and consumer awareness increases, compliance failures or documentation gaps can lead to market access delays, reformulation costs, or reputational impact. Investing in regulatory intelligence and quality assurance is therefore both an opportunity enabler and a risk mitigation measure.
Trend Three: Supply Chain Diversification and Cost Management Will Remain Central
Raw material volatility and trade dynamics will continue to influence cost structures and supply security through the forecast period. The experience of 2025, with notable import price fluctuations, reinforces the need for diversified sourcing, forward planning, and resilient logistics. Companies that can balance cost efficiency with supply reliability will be better equipped to maintain margins and meet customer expectations in a fluctuating environment.
Commercial opportunities arise from supply chain sophistication itself. Buyers seeking stability will value suppliers with demonstrated sourcing diversification, inventory management, and risk mitigation practices. Suppliers that can offer transparency into origin, quality verification, and contingency planning will differentiate themselves in a market where reliability is increasingly prized alongside price.
Risks and Uncertainties to Monitor
Several risks could alter the trajectory of the licorice extract market. Agricultural yield variability and climate-related disruptions in key growing regions could amplify raw material price swings and constrain supply. Regulatory changes, particularly around glycyrrhizin thresholds or labeling requirements, could force reformulation or limit certain application segments. Trade policy shifts or freight cost escalation could affect import-dependent markets and alter competitive dynamics between regional and global suppliers. Additionally, if functional claims face heightened scrutiny or if consumer preferences shift away from certain flavor profiles, demand growth in specific segments could moderate.
Participants should monitor these factors through continuous market intelligence, supplier engagement, and scenario planning. Flexibility in sourcing, formulation, and application focus will be valuable in navigating an environment where multiple variables can shift within a single forecast cycle.
Strategic Recommendations for Decision-Makers
For Manufacturers and Suppliers
Focus on format and application breadth as a foundation for customer retention and expansion. Offering a range of powder, block, paste, and liquid options, supported by consistent quality and documentation, enables manufacturers to serve diverse processing requirements and reduce the likelihood of customer churn. Invest in extraction and formulation capabilities that support standardized potency, functional compound profiles, and region-specific compliance. Differentiation through proprietary or specialized extracts can open premium pathways in functional food, nutraceutical, and cosmetic segments.
Strengthen supply chain resilience by diversifying sourcing origins, securing long-term agreements where feasible, and implementing robust quality verification and inventory planning. In a market sensitive to raw material price volatility, operational discipline in cost management and supply continuity will protect margins and reinforce buyer confidence.
For Investors and Strategic Planners
Evaluate opportunities based on the intersection of application growth, regulatory clarity, and supplier capability. Segments with established regulatory pathways and growing consumer interest, such as functional foods and select nutraceutical applications, offer attractive growth potential but require credible quality systems and documentation. Assess target companies or partners for format flexibility, extraction expertise, compliance competence, and supply chain diversification, as these factors increasingly determine competitive durability.
Monitor consolidation trends and trade dynamics, as concentration and import dependency can shape pricing power, market access, and competitive intensity. Consider scenario analysis around raw material volatility and regulatory changes to stress-test investment assumptions and identify resilience requirements.
Licorice Root Extracts For Food And Beverage Market
For Procurement and Sourcing Leaders
Expand vendor evaluation criteria beyond unit cost to include regulatory documentation, format capabilities, application support, and supply continuity practices. In a market where compliance requirements vary by region and raw material costs can fluctuate, suppliers with strong quality systems, transparent sourcing, and diversified supply bases offer greater long-term value. Establish clear specifications for glycyrrhizin content, purity, and documentation to streamline compliance and reduce reformulation risk.
Develop a balanced sourcing strategy that combines cost competitiveness with supply security. Where feasible, maintain multiple qualified suppliers across regions or formats to mitigate disruption risk and preserve negotiating leverage. Request regular updates on sourcing origins, quality verification, and regulatory compliance to stay ahead of changing requirements.
Mapping the Path Forward
The licorice extract market is entering a phase where growth is supported by steady demand across traditional applications, while value creation increasingly depends on innovation, compliance excellence, and supply chain resilience. The 5.4 percent compound annual growth rate projected through 2032 reflects a market that is expanding but not booming, making strategic execution and differentiation more important than volume alone. Companies that align their capabilities with functional application opportunities, regulatory demands, and supply chain realities will be best positioned to capture sustainable value.
For decision-makers seeking to navigate this landscape with confidence, detailed segment-level data, competitive profiling, and customized sourcing or investment recommendations can provide the granularity needed to translate market-level insights into specific actions. Exploring a comprehensive market report can help clarify segment dynamics, benchmark supplier capabilities, and identify the most relevant opportunities for a given business context.
For detailed analysis of this topic, please visit the official page: Licorice Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
ECMO Systems Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and Core Challenges
The extracorporeal membrane oxygenation (ECMO) systems market has evolved from a niche intensive-care intervention into a structural component of modern critical care and cardiac surgery pathways. Valued at approximately USD 450 million in 2025, the market has expanded from a lower base observed across 2020-2025, reflecting sustained adoption in high-acuity settings and broader institutional familiarity with extracorporeal life support. Forward projections through 2032 indicate a trajectory toward USD 611 million, translating to a compound annual growth rate of roughly 4.5 percent. This pace signals steady, rather than explosive, growth—one shaped by clinical adoption curves, reimbursement realities, and the gradual standardization of ECMO across hospitals and transport networks rather than by sudden demand shocks.
At this stage of maturity, the industry faces several inflection points that will determine whether growth is broadly shared or concentrated among a smaller set of capable players. First, reimbursement and coding frameworks remain fragmented and, in many markets, lag behind clinical practice. Hospital payment structures for non-operative ECMO pathways have been shaped by DRG assignments that date back to 2018 and continue to influence net payments for peripheral veno-venous and veno-arterial configurations. These legacy payment rules create variability in the economic case for ECMO programs, especially for centers evaluating whether to expand services, invest in transport-capable systems, or adopt higher-complexity configurations. Second, staffing and training models are under pressure. As ECMO use broadens across respiratory, cardiac, and emergency cardiopulmonary resuscitation indications, centers must reconcile clinical competence requirements with workforce constraints. Emerging evidence supports advanced practice-provider and nurse-led management models that can match perfusionist-led outcomes while reducing personnel costs, but implementation depends on local governance, credentialing, and simulation-based training standards. Third, the market’s concentration profile suggests a competitive environment where scale, regulatory readiness, and integrated product ecosystems matter more than ever. With a meaningful share held by a small group of leading manufacturers, smaller or regional players must differentiate through niche configurations, pediatric and neonatal suitability, transport robustness, or service and training bundles rather than competing purely on console price.
For decision-makers, the core implication is that ECMO is no longer a pure device story. It is a program-level investment that ties together hardware, oxygenators, cannulas, training, staffing, transport logistics, and reimbursement strategy. Organizations that treat ECMO as a bundled capability—rather than a point purchase—are better positioned to manage total cost of care, expand service lines, and respond to clinical guideline updates that increasingly emphasize competency, simulation, and structured protocols across patient populations, including specialized use cases such as peripartum support.
Key Demand Drivers
Technology Innovation and Device Simplification
Technology momentum is reshaping the value proposition of ECMO systems around portability, configurability, and ease of use. The industry is moving toward platforms that can serve multiple clinical scenarios—short-term support, prolonged extracorporeal life support, intra-hospital use, and transport—without requiring separate equipment inventories. This convergence is appealing to hospitals that want to standardize logistics, reduce training overhead, and improve responsiveness during transfers or surge events. A notable example is the European launch of a configurable one-system ECMO solution at the EACTS Annual Meeting in October 2025, following regulatory clearance. Broader availability of such platforms signals a shift from single-use, indication-specific purchasing toward flexible systems that can be redeployed across respiratory, cardiac, and emergency support pathways.
Alongside console-level innovation, oxygenator and pump technologies continue to influence clinical usability. Advanced circulatory support pumps and dedicated ECMO oxygenators are being positioned to improve integration, reduce priming complexity, and support a wider range of patient sizes. These improvements matter not only for clinical performance but also for program economics, because simpler setups can reduce setup time, lower the burden on specialized staff, and make ECMO more accessible in centers that do not run high volumes daily. In practical terms, device simplification expands the addressable setting for ECMO beyond large tertiary centers, particularly when paired with transport-ready designs and clearer reimbursement documentation.
Policy, Regulation, and Training Standards
The regulatory and clinical-guideline environment is becoming more structured, and that structure is itself a growth enabler. Recent ECMO-related guidance and certification activity points to a maturing ecosystem in which training, simulation, and competency-based curricula are treated as integral to safe service delivery. In November 2025, ELSO released a narrative guideline on ECMO training and continuing education, emphasizing competency-based curriculum and simulation for centers. This type of framework helps normalize ECMO adoption by giving institutions a recognized reference point for staff development, quality assurance, and service-line expansion. It also raises the importance of manufacturers and service providers that can offer aligned training resources, simulation support, and clinical documentation tools.
Regulatory approval pathways and market-specific conformity requirements continue to influence launch timing and geographic reach. Multinational participants are moving products through region-specific approvals and updating systems to meet current medical device regulations, as seen with a neonatal-to-adult ECMO system approved under MDR and announced for broad patient coverage in October 2024, with the active system positioned for 2025. The practical consequence is that time-to-market is increasingly tied to regulatory readiness and documentation quality, not just engineering capability. For commercial teams, this means launch strategy, clinical evidence packages, and post-market support should be planned as interconnected workstreams rather than sequential steps.
Demand-Side Shifts and Care Models
Demand for ECMO is being shaped less by a single clinical trend than by a set of care-model changes. Respiratory support remains a central application area, while cardiac indications and emergency resuscitation use continue to broaden the clinical footprint of extracorporeal support. As a result, hospitals are evaluating ECMO not only as a rescue therapy but also as part of a wider critical-care and surgical service strategy. This shift is visible in the way programs are becoming more deliberate about patient selection, inter-facility transport, and the use of structured protocols for special populations, including pregnancy and peripartum care.
The staffing conversation is equally important. Evidence from critical-care nursing sources suggests that nurse-led advanced practice-provider models for ECMO management can deliver survival and complication outcomes comparable to perfusionist-led models while reducing personnel costs. For healthcare administrators, this opens a path to scaling ECMO services without necessarily expanding highly specialized staffing in proportion to volume. It also encourages the development of mixed-service models in which specialized expertise is concentrated at key nodes and supported by trained advanced practice staff at satellite sites or during transport. The broader impact is that demand is increasingly sensitive to operational feasibility: systems that are easier to manage, easier to train staff on, and easier to integrate into existing workflows will be favored in purchasing and program planning.
Supply Chain, Cost Structures, and Total Cost of Ownership
Cost structures in ECMO are shifting from device acquisition toward total cost of ownership. Hospital purchasers are increasingly weighing disposables, oxygenator longevity, integration with existing cannulation and monitoring setups, service agreements, and training costs. Reimbursement dynamics remain a central variable: updated reimbursement guidance from a major manufacturer in October 2025 outlined intraoperative billing considerations and local physician rates for ECMO support, underscoring how documentation and billing precision can affect program economics. Meanwhile, DRG assignment frameworks for non-operative ECMO pathways continue to influence how hospitals are paid, reinforcing the need for procurement decisions to align with coding and billing realities.
These factors favor suppliers that can offer predictable consumable formulations, clear service support, and practical reimbursement documentation tools. They also reward manufacturers that reduce complexity in the field—through integrated systems, standardized kits, and configurations suitable for neonates, pediatrics, and adults alike—because such attributes lower implementation friction and reduce hidden costs associated with training, error management, and device swaps. For investors and strategists, the cost conversation is no longer just about unit pricing; it is about whether a system lowers the operating burden of running a reliable ECMO program across multiple sites and clinical scenarios.
Competitive Landscape and Leading Strategies
The competitive field is defined by a small number of mature participants with strong regulatory positions, established clinical footprints, and increasingly differentiated platform strategies. Medtronic, based in Ireland, offers a configurable one-system ECMO solution designed for critically ill patients, with European launch completed in 2025. This move reflects a strategy centered on flexibility and multi-scenario use, positioning the platform for hospitals that want to cover respiratory, cardiac, and transport needs without managing multiple device families. The October 2025 European launch at the EACTS Annual Meeting, following CE mark approval, illustrates a deliberate regional rollout tied to major clinical forums and regulatory milestones.
Getinge, headquartered in Sweden, provides Cardiohelp II and Rotaflow II ECMO systems designed for short-term or prolonged extracorporeal life support, including intra-hospital and transport use. This portfolio emphasizes operational versatility and established clinical familiarity, which is valuable for centers that need reliability across a range of support durations and care settings. Getinge’s positioning suggests a continued focus on proven system performance and transport readiness rather than radical platform change, appealing to institutions that prioritize continuity and broad procedural compatibility.
LivaNova, based in the United Kingdom, supplies an advanced circulatory support pump and controller system alongside an ECMO oxygenator. This combination supports a strategy built on integration between pumping technology and gas exchange components, targeting centers that value cohesive system architecture and a well-defined component ecosystem. For buyers, such integration can simplify supply consistency and streamline clinical workflows where pump and oxygenator selection are closely linked.
Intra-Aortic Balloon Pump (IABP) Market
Terumo, headquartered in Japan, manufactures ECMO and extracorporeal life support systems for cardiac surgery and emergency care, commercially available in Japan and select Asian countries. This regional availability points to a strategy tied to local clinical demand and regulatory access, with potential for deeper adoption in markets where cardiac surgery and emergency support pathways are expanding. Terumo’s approach emphasizes geographically targeted commercialization and clinical alignment with cardiac and emergency use cases.
Fresenius Medical Care, through Xenios AG and headquartered in Germany, provides a console and patient kits for ECMO approved for all patients from neonates to adults, with an MDR-approved system announced in October 2024 and active in 2025. This broad patient coverage is a meaningful differentiator because it addresses a structural purchasing preference for systems that can span neonatal, pediatric, and adult care without requiring separate device programs. For network-level buyers and integrated delivery organizations, such breadth can simplify inventory planning and training across age groups and care settings.
Taken together, the competitive landscape is evolving along three axes. First, integration and configurability are becoming more important than single-function excellence, as hospitals seek platforms that can be redeployed across indications and settings. Second, geographic and regulatory readiness is increasingly a competitive differentiator, because launch timing and market access can determine early share gains in regions with growing ECMO programs. Third, service, training, and reimbursement enablement are moving from supporting activities to core competitive elements, especially as centers look to scale programs efficiently and safely. While the market remains concentrated among leading participants, the trend does not preclude new entry in focused segments—particularly where a company can offer a differentiated value proposition in pediatric and neonatal suitability, transport robustness, or program-enabling services—but such entry will likely depend on clear clinical evidence, regulatory alignment, and strong implementation support.
Forward-Looking Trends and Strategic Implications
Over the next three to five years, several trends are likely to shape ECMO commercial opportunity. The first is platform convergence around transport-ready, configurable systems that can serve respiratory, cardiac, and emergency support without requiring separate inventories. This trend favors organizations that can reduce operational complexity and help hospitals standardize equipment, training, and logistics across sites. The commercial opportunity lies not only in selling consoles but in enabling broader program adoption through kits, consumables, training, and documentation support that make multi-site deployment feasible.
The second trend is the increasing formalization of training and competency standards. As ELSO guidelines and similar frameworks reinforce simulation-based competency and continuing education, centers will look for suppliers and partners that can align with these expectations. This creates an opportunity for companies to build differentiated service offerings around implementation, credentialing support, and quality documentation. It also introduces an execution risk: organizations that treat training as an afterthought may face slower adoption, higher error rates, and more resistance from clinical leadership concerned about safety and consistency.
The third trend is the continued pressure to align clinical use with reimbursement and operational economics. Payment frameworks and billing guidance will remain important determinants of program viability, especially for non-operative pathways and complex patient populations. Suppliers and healthcare organizations that invest in reimbursement clarity, coding precision, and cost-effective staffing models will have an advantage in expanding services sustainably. At the same time, uncertainty remains. Reimbursement changes can be slow and vary by market, regulatory pathways can delay launches, and staffing models may be constrained by local policies and institutional culture. These factors mean that growth will likely be sequential and program-dependent rather than uniform across regions or hospital types.
PW Consulting
From a strategic standpoint, these trends create clear commercial opportunities. Manufacturers can pursue differentiation by combining flexible hardware with strong service and training ecosystems, so that their systems are easier to adopt, easier to scale, and easier to bill correctly. Investors can look for players with credible regulatory execution, broad patient coverage, and evidence of operational advantages in staffing or transport. Healthcare buyers can prioritize systems and partners that reduce total program burden, support competency-based training, and fit within existing reimbursement pathways, rather than optimizing solely on purchase price.
Actionable Guidance for Decision-Makers
For manufacturers and commercial leaders, the priority is to treat ECMO as a program-level proposition rather than a device transaction. This means aligning product design, regulatory planning, clinical evidence, and reimbursement support so that a single platform can be deployed across multiple indications and patient populations. Companies should reinforce differentiation through configurability, transport readiness, and clear suitability across adults, pediatrics, and neonates, while building the training and service infrastructure needed to support safe scaling. Commercial messaging should emphasize operational feasibility and total cost of care, especially where staffing models and billing documentation can materially affect adoption.
For investors, the strategic question is whether a company’s capabilities match where the market is heading. The most resilient opportunities are likely to be found in participants with strong regulatory execution, broad clinical applicability, and credible support for program implementation. Attention should be paid to evidence of multi-scenario use, patient-coverage breadth, and the ability to reduce hidden costs through integrated consumables, service, and training. Given ongoing reimbursement and staffing uncertainties, due diligence should include an assessment of how well a company helps customers navigate coding, billing, and workforce requirements, since these factors increasingly determine the pace of adoption.
For healthcare procurement and program leaders, purchasing decisions should be evaluated in the context of total program economics. Systems that support consistent workflows, reduce training burden, and enable safe transport or multi-site use may offer greater long-term value than lower upfront device costs alone. It is also prudent to align procurement with staffing strategy, training standards, and reimbursement documentation, particularly where nurse-led or advanced practice-provider models are being considered. Procurement teams should request clear evidence of suitability across the patient populations they serve, as well as support materials that help centers meet competency and simulation expectations.
Artificial Heart Lung Machines Market
For decision-makers seeking a deeper, segmented view of market size, regional dynamics, modality and application splits, patient-type demand patterns, and competitive positioning, a more detailed research report can provide the granularity needed for planning, investment screening, and procurement comparisons. Tailored analysis is especially useful when evaluating launch timing, reimbursement alignment, and segment-specific growth prospects across regions and clinical pathways.
For detailed analysis of this topic, please visit the official page: Extracorporeal Membrane Oxygenation (ECMO) Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Sucker Rod Market 2026: Why 5.5% CAGR Trajectory and $3.07B Forecast Redefine Strategy
By PW Consulting, 2026-09-21
The Sucker Rod Market: Strategic Shifts, Competitive Dynamics, and Commercial Opportunities Through 2032
The global sucker rod market is entering a period of sustained expansion, driven by a combination of mature basin optimization, deeper well interventions, and evolving material technologies. From a base valuation of 1.55 billion USD in 2020, the market has climbed to 2.1 billion USD in 2025 and is projected to reach 3.07 billion USD by 2032, reflecting a compound annual growth rate of 5.5 percent across the forecast window. Rather than signaling a simple volume rebound, this trajectory points to a structural recalibration in how artificial lift systems are specified, manufactured, and sustained. Operators are balancing cost constraints with performance demands, while manufacturers are pressured to differentiate through metallurgical innovation, lifecycle services, and supply chain resilience. Understanding the forces shaping this market requires moving beyond headline figures to examine the convergence of technical, regulatory, and competitive drivers that will define commercial decision-making over the next several years.
At the center of this evolution lies a market that is large enough to attract global participation yet concentrated enough to reward strategic positioning. The competitive field features established North American and European integrated players alongside a dense cluster of Chinese manufacturers scaling production capacity, and a growing cohort of service-oriented firms specializing in remanufacturing and specialty alloys. Value creation is shifting from pure volume production toward engineered solutions, corrosion-resistant configurations, and total-cost-of-ownership models. For executives and investors navigating upstream equipment procurement or industrial manufacturing portfolios, the sucker rod segment offers a lens into broader oilfield services trends: the push for longer well life, the integration of monitoring and material science, and the regionalization of supply chains under shifting trade and compliance frameworks.
Market Overview and Core Tensions
The five-year backward and forward trajectory outlines a market that has already absorbed the post-downturn recovery and is now moving into a growth phase anchored by steady onshore activity and selective offshore deployment. The expansion from 1.98 billion USD in 2023 to an estimated 2.1 billion USD in 2025, followed by a progressive climb toward the 3 billion USD threshold by 2032, underscores that demand is not cyclical in the traditional sense but is being reinforced by operational requirements that favor continuous rod lift systems. The pace of growth, averaging 5.5 percent annually, suggests that incremental efficiency gains, well remediation programs, and the replacement of aging lift infrastructure are sustaining order books even as capital discipline remains prominent across exploration and production portfolios.
Beneath this steady expansion, however, lie several structural tensions that executives must monitor closely. First, raw material price volatility continues to inject uncertainty into cost planning and margin management. Steel price movements, particularly the trajectory observed in mid-2025 with average pricing around 885 USD per metric ton and potential increases in galvanized processing costs linked to iron ore and zinc dynamics, directly affect the economics of steel-based rod manufacturing. Manufacturers and buyers alike are navigating pricing environments where input cost shifts can compress profitability or force renegotiation of long-term supply agreements. Second, regulatory and compliance architectures are layering additional complexity onto cross-border procurement. Active licensing requirements tied to API 11B standards, continued oversight of Chinese-origin imports in certain markets, and periodic updates to performance standards by agencies such as the U.S. Environmental Protection Agency are reshaping how products are certified, sourced, and deployed. The absence of a major revision to the API 11B specification in 2025 may offer short-term continuity, but the surrounding compliance ecosystem remains dynamic, especially for manufacturers exporting across jurisdictions with distinct certification and inspection regimes.
Nylon Rod Market
Third, the market faces a performance-versus-cost inflection point as operators increasingly prioritize longevity and downtime reduction over lowest upfront price. As wells are pushed deeper, exposed to more corrosive environments, and expected to maintain production with fewer interventions, the commercial conversation is shifting toward total lifecycle value. This dynamic is reshaping procurement behavior, encouraging specification of premium rod grades, corrosion-resistant configurations, and remanufactured or reinforced components that extend run-life. The tension is not simply about cost but about aligning material selection and service models with the economic realities of each asset class, from mature onshore fields to offshore installations where weight, fatigue resistance, and energy efficiency carry heightened importance.
Open Hole Packers Market
Key Drivers Reshaping Demand and Supply
The market’s progression is being propelled by a set of interlocking drivers that are altering both what operators require and how manufacturers respond. Technological innovation stands out as a primary catalyst. Advanced rod designs and material formulations are enabling performance in wells that were previously considered marginal or too demanding for conventional configurations. Induction case-hardening, high-strength steel grades, and fiberglass alternatives are expanding the envelope of application, particularly where fatigue resistance, corrosion performance, and weight reduction matter. Recent product showcases and announcements from leading suppliers highlight a deliberate push toward rods engineered for extreme hardness and well productivity enhancement, including fiberglass solutions targeted at reducing energy consumption in offshore operations. These developments are not isolated product launches; they indicate a broader industry movement toward rod systems that integrate material science with operational efficiency, enabling operators to extract more value from challenging reservoirs while managing operating expenses.
Policy and regulatory environments are simultaneously shaping market behavior by reinforcing specification rigor and creating compliance considerations that influence sourcing decisions. The continued prominence of API 11B standards, recent product data sheet updates from major manufacturers, and industry workshops focused on best practices underscore an ecosystem where technical compliance and performance validation are integral to market access. At the same time, regulatory actions that extend performance standards deadlines or affect broader oil and gas production compliance introduce indirect pressure on equipment lifecycles and operational planning. Import oversight and licensing requirements in certain regions add a further layer of due diligence for multinational operators and manufacturers, rewarding suppliers that can demonstrate consistent certification, traceability, and documentation. These dynamics are nudging the market toward greater standardization in quality expectations while also encouraging regional supply strategies that mitigate cross-border friction.
Demand-side shifts are redefining procurement priorities and accelerating the adoption of engineered solutions over commoditized alternatives. Operators managing aging onshore fields are seeking rods and components that reduce failure rates and maintenance frequency, while offshore and deeper well applications are placing a premium on corrosion resistance, weight optimization, and fatigue durability. The commercial mindset is increasingly oriented around well run-life and total cost of ownership rather than unit price alone. This shift is reinforced by the growing integration of monitoring capabilities and service offerings that tie rod performance to broader artificial lift optimization. When manufacturers and service providers can demonstrate how advanced rod configurations, remanufacturing processes, or specialty couplings contribute to fewer interventions and longer intervals between workovers, the commercial case for premium specifications becomes more compelling, especially in fields where downtime carries significant opportunity cost.
Supply chain and cost structure changes are completing the driver set by forcing manufacturers to rethink sourcing, production footprint, and value-added services. Steel price volatility, galvanized processing cost pressures, and the logistics of maintaining consistent quality across multiple production sites are compelling firms to balance scale with specialization. Some manufacturers are responding by emphasizing domestic or regionally anchored production to serve customers who prioritize supply certainty and reduced lead times, while others are leveraging global manufacturing footprints to compete on volume and cost. At the same time, remanufacturing and reinforcement services are gaining strategic relevance as a way to extend asset life and capture value from the existing installed base. The combination of material cost pressures, compliance considerations, and the demand for lifecycle solutions is pushing the market toward a more diversified competitive structure, where success depends on both production efficiency and the ability to deliver differentiated performance outcomes.
Competitive Landscape and Strategic Positioning
The competitive field reflects a blend of integrated global manufacturers, regionally focused producers, and service-oriented specialists, each occupying distinct strategic niches. In North America, a privately held domestic manufacturer has carved out a position as the only privately owned and operated domestic sucker rod producer in the United States, emphasizing API-grade steel rods and components manufactured at its Midwest facility. This positioning appeals to customers who value domestic supply continuity, localized technical support, and direct accountability across the production chain. Alongside this domestic contender, several larger North American and international players compete through premium material technologies and integrated artificial lift portfolios. One prominent supplier has built a reputation around high-strength rods and fiberglass configurations with induction case-hardening, designed to improve fatigue resistance and corrosion performance in demanding wells. This company’s recent activities, including fiberglass rod announcements aimed at offshore energy efficiency and advanced rod solutions showcased for extreme hardness in rod lift and PCP applications, illustrate a strategy centered on technical differentiation, application-specific engineering, and active engagement with industry forums where specification preferences are shaped.
PW Consulting
European and globally distributed manufacturers contribute scale, international certification breadth, and a portfolio of API-compliant rods and special grades tailored for rod lift applications. Their competitive advantage often lies in the ability to serve multinational operators with consistent specifications across regions, supported by manufacturing facilities that can respond to varied project requirements. The recent product data sheet updates and continued alignment with API 11B expectations reinforce a market posture that emphasizes compliance readiness and technical documentation as part of the value proposition. For operators managing portfolios across multiple jurisdictions, such global consistency can reduce procurement complexity and support standardized asset management strategies.
A substantial cohort of Chinese manufacturers represents another layer of the competitive landscape, spanning CNPC-affiliated operations, cost-focused producers, and specialized equipment makers serving upstream petroleum applications. These firms collectively emphasize alloy and carbon steel rods, continuous rod production, and cost-effective solutions for global oilfield operations, with varying degrees of API-compliant manufacturing and regional distribution footprints. Their presence has broadened competitive options for buyers seeking volume supply, price competitiveness, and growing technical capabilities. At the same time, the market context surrounding Chinese-origin imports, including active licensing requirements in certain jurisdictions, means that exporters and buyers must navigate compliance and certification processes carefully. This environment rewards manufacturers that can pair competitive cost structures with transparent quality assurance, clear documentation, and the ability to meet region-specific standards.
Beyond new-production manufacturers, a distinct segment of the market is emerging around remanufacturing, reinforcement, and specialty component innovation. Remanufacturing specialists that reprocess used steel rods with enhanced performance characteristics, alongside suppliers of advanced alloy couplings designed for superior wear and corrosion resistance, are expanding the definition of value in the sucker rod ecosystem. These offerings appeal to operators seeking to extend well run-life, reduce material consumption, and lower the total cost of lift operations. Providers of corrosion-resistant rod series and high-performance artificial lift components further illustrate how product portfolios are broadening to address harsh environments and integrated lift solutions. The presence of firms focused on ISO 9001 and API 11B compliant manufacturing at licensed facilities, as well as suppliers integrating rod pumps and components into broader artificial lift packages, highlights a market where service integration, quality certification, and application-specific engineering are increasingly important competitive dimensions.
Strategic positioning across this landscape is coalescing around three broad patterns. First, premium differentiation through material science and application-specific engineering is enabling select players to command preference in demanding wells and offshore settings, where performance and reliability carry heightened economic weight. Second, regional and domestic supply positioning is gaining traction among customers who prioritize production locality, lead-time certainty, and regulatory alignment, particularly in markets where import oversight and licensing requirements add friction to cross-border procurement. Third, lifecycle services and remanufacturing are becoming strategic levers for capturing value from the installed base, extending asset life, and offering alternatives to full replacement cycles. These patterns suggest a market that is not simply consolidating or fragmenting but stratifying around value propositions tied to performance, compliance readiness, supply certainty, and total lifecycle economics. New entrants and expanding producers are likely to find opportunities by combining credible certification and quality systems with clear technical advantages or cost-efficient service models, rather than competing on volume alone.
Forward Trends and Commercial Implications
Looking ahead to the 2026 through 2032 window, three strategic trends are likely to shape how the market evolves and where commercial opportunities emerge. The first is the continued shift toward performance-engineered rod systems and material innovation as operators push for longer well life and reduced intervention frequency. High-strength configurations, corrosion-resistant variants, fiberglass alternatives for weight-sensitive offshore applications, and advanced couplings that improve wear and corrosion resistance are expected to gain additional traction as operators quantify the economic benefits of extended run-life and fewer workovers. Commercial opportunities in this trend favor manufacturers and service providers that can validate performance claims with field data, offer application-specific recommendations, and bundle rods with complementary components or monitoring capabilities that enhance lift efficiency. The opportunity is not merely to supply hardware but to help operators reduce total cost of ownership in environments where downtime and corrosion-related failures directly affect cash flow.
The second trend is the growing importance of compliance-ready, regionally aligned supply strategies. As certification expectations remain firm and import oversight continues in specific jurisdictions, suppliers that can demonstrate consistent API 11B alignment, strong documentation practices, and transparent quality assurance will be better positioned to secure contracts with multinational operators and regionally focused buyers alike. This trend also supports regional production and distribution strategies that reduce lead times and mitigate the uncertainty associated with cross-border trade complexities. Commercial opportunities here include partnerships with operators seeking supply diversification, localization of critical components, and reliable availability for mature fields that cannot afford performance interruptions. Manufacturers that invest in certification infrastructure, traceability, and regional presence can convert compliance requirements from a constraint into a competitive advantage.
The third trend is the elevation of remanufacturing, reinforcement, and lifecycle services as core elements of the market rather than ancillary offerings. As steel and processing costs remain volatile and operators seek to optimize capital deployment, the ability to restore used rods to enhanced performance levels, reinforce critical components, and integrate rod solutions with artificial lift services becomes increasingly valuable. This trend opens commercial pathways for firms that can combine reprocessed or reinforced products with quality guarantees and technical support, effectively competing on value over the full asset cycle. It also creates opportunities for specialty alloy suppliers and component innovators whose products extend service intervals and reduce failure rates in harsh environments. The commercial case will strengthen where providers can demonstrate measurable reductions in downtime, material waste, and replacement frequency, particularly in onshore mature fields and offshore installations where operational continuity is paramount.
These trends carry inherent uncertainties that decision-makers should monitor. Raw material price volatility and processing cost movements can reshape margin dynamics and alter the attractiveness of certain material choices over time, making it important to structure procurement and pricing strategies with flexibility. Regulatory and compliance developments, including changes in import oversight, licensing expectations, and broader environmental performance standards, may shift sourcing patterns or add administrative burdens that affect lead times and cost structures. In addition, the pace of adoption for advanced rod technologies and fiberglass alternatives will depend on operator willingness to validate new configurations in demanding settings, which can vary by basin, well type, and organizational risk tolerance. Finally, competitive intensity may increase as manufacturers expand capacity, service providers broaden lifecycle offerings, and regional supply networks evolve, potentially compressing returns in commoditized segments while rewarding differentiated positions.
Strategic Actions for Decision-Makers
For manufacturers and product developers, the priority is to anchor competitive positioning in verifiable performance outcomes and compliance readiness rather than volume positioning alone. Investing in material innovation, application-specific engineering, and robust quality documentation can create defensible differentiation, especially in demanding onshore and offshore applications where failure cost is high. Equally important is evaluating lifecycle service opportunities, including remanufacturing, reinforcement, and coupling solutions that extend well run-life, as these can diversify revenue and deepen customer relationships beyond initial equipment sales. Manufacturers should also stress-test their supply strategies against steel price volatility and processing cost pressures, considering regional production or distribution options that improve resilience and shorten response times for key customers. Building clear technical narratives around fatigue resistance, corrosion performance, energy efficiency, and total cost of ownership will help translate product capabilities into commercial advantage in procurement discussions.
For investors and portfolio managers, the market’s trajectory suggests opportunities in companies that combine technical differentiation with credible compliance systems and service-oriented business models. The growth path from 2025 toward 2032 indicates sustained demand, but returns will likely be uneven across segments, favoring players that can capture premium specifications, lifecycle value, and supply-chain resilience. Due diligence should focus on certification maturity, regional supply positioning, exposure to raw material volatility, and the ability to deliver value beyond new rod production through remanufacturing or integrated lift services. In markets where import oversight and licensing requirements are active, the capability to navigate compliance efficiently can be a meaningful barrier to entry and a source of durable advantage. Investors should also monitor the adoption curve for fiberglass and premium steel configurations, as well as the expanding role of monitoring-integrated rod solutions, since these can reshape competitive positioning and demand patterns over the forecast period.
For operators, procurement teams, and engineering leads, the strategic emphasis should be on aligning rod specification with asset economics and operational risk rather than defaulting to lowest initial cost. Evaluating total cost of ownership, including expected run-life, maintenance frequency, corrosion risk, and downtime impact, can reveal cases where premium grades, corrosion-resistant configurations, or remanufactured and reinforced components deliver better long-term economics. Procurement strategies should also incorporate supply assurance considerations, such as certification documentation, regional availability, and supplier ability to meet region-specific compliance expectations, in order to reduce exposure to lead-time uncertainty and import-related friction. Where applicable, integrating rod selection with broader artificial lift optimization and monitoring initiatives can further improve efficiency and extend productive intervals. Decision-makers should weigh the trade-offs between standard and specialized solutions on a field-by-field basis, recognizing that the optimal specification often depends on well conditions, production profile, and the economic consequence of failure.
As the market continues its advance toward the 2032 horizon, staying current with material developments, compliance expectations, and competitive moves will be essential for capturing value and avoiding stranded decisions. Detailed segmentation data, company-level profiling, and region- and application-specific demand patterns can sharpen procurement timing, investment allocation, and product strategy in ways that high-level market figures cannot fully convey. Accessing granular, up-to-date research on pricing dynamics, certification trends, and supplier capabilities can help executives convert broad market momentum into targeted actions that improve procurement outcomes, portfolio returns, and operational reliability across the artificial lift lifecycle.
For detailed analysis of this topic, please visit the official page: Sucker Rod Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com